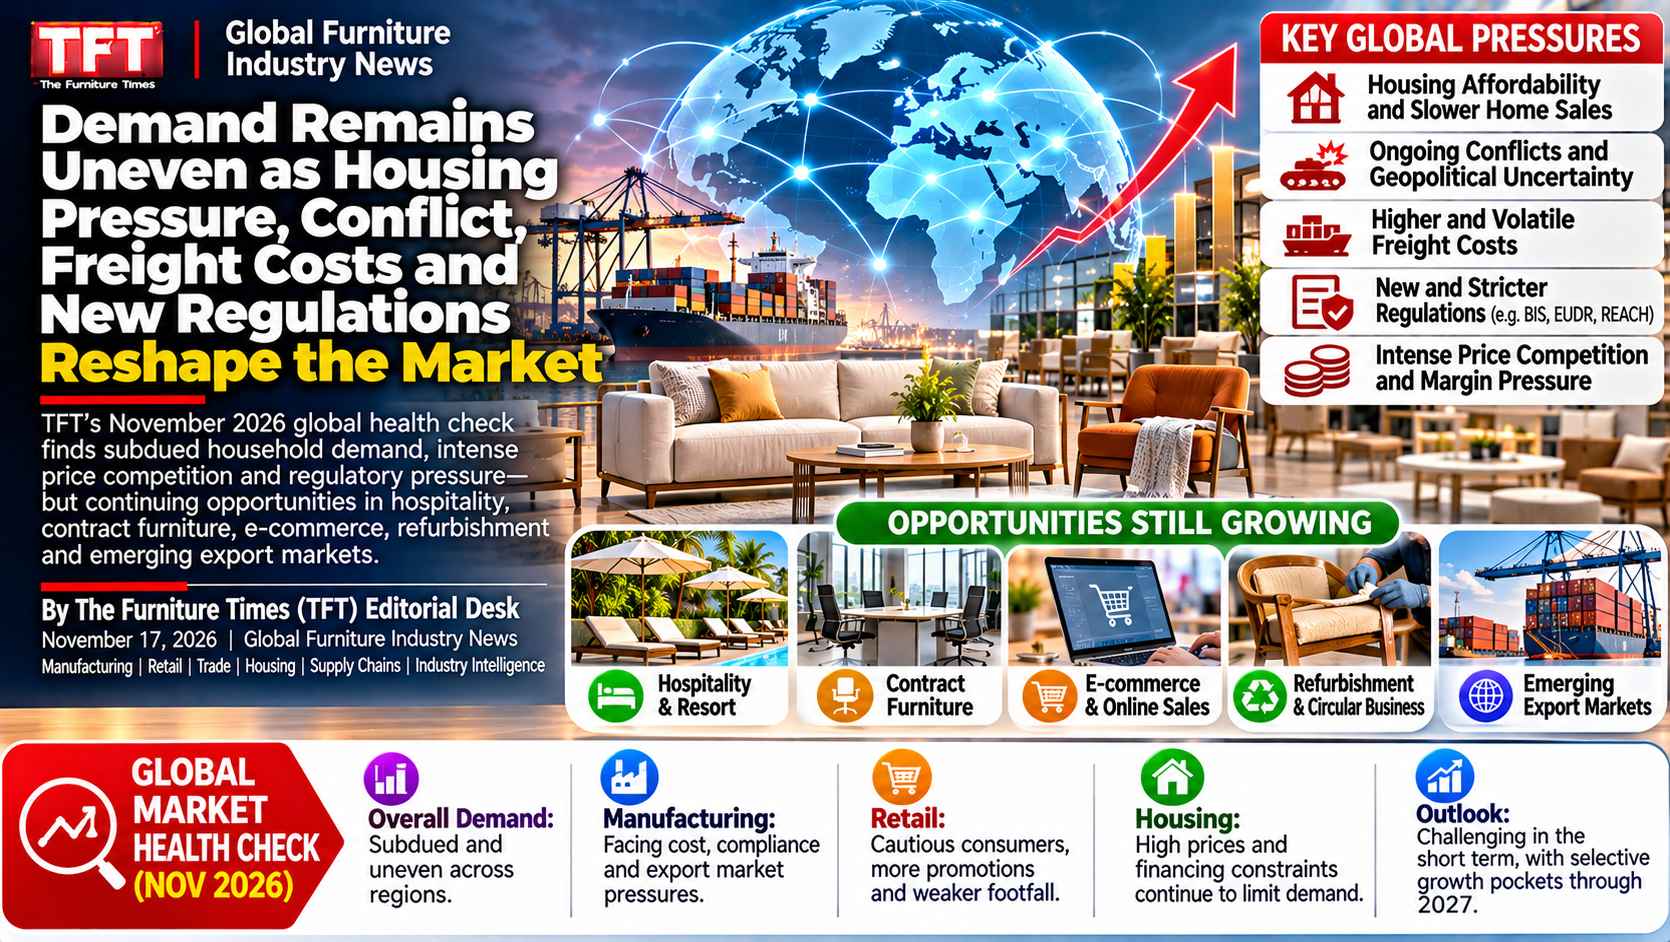
Global Furniture Industry News: Demand Remains Uneven as Housing Pressure, Conflict, Freight Costs and New Regulations Reshape the Market
TFT’s November 2026 global health check finds subdued household demand, intense price competition and regulatory pressure—but continuing opportunities in hospitality, contract furniture, e-commerce, refurbishment and emerging export markets
By The Furniture Times (TFT) Editorial Desk | November 17, 2026 | Global Furniture Industry News | Manufacturing | Retail | Trade | Housing | Supply Chains | Industry Intelligence
The global furniture industry is approaching the end of 2026 without a single, unified recovery.
Instead, the market is becoming more divided.
Residential furniture demand remains constrained in several major economies by expensive housing, cautious consumers and slower property activity. Retailers are increasing promotions to protect sales, while manufacturers face volatile freight costs, geopolitical uncertainty, regulatory deadlines and continuing pressure to reduce prices.
At the same time, opportunity has not disappeared.
Hospitality development, tourism investment, office refurbishment, healthcare, institutional procurement, urban housing and commercial replacement demand continue supporting selected categories. Southeast Asian manufacturing centres are adjusting their export strategies, while companies in mature markets are investing in premium products, digital retail, circular services and supply-chain diversification.
The industry’s condition in November 2026 can be summarised in one sentence:
Furniture is not experiencing a universal collapse or a broad-based boom; it is undergoing a difficult restructuring in which demand, production and market power are shifting between countries, channels and product categories.
Global Furniture Industry Health Check: November 2026
| Indicator | Current assessment | Furniture-industry implication |
|---|---|---|
| Residential demand | Weak to mixed | Fewer home moves and pressured affordability are delaying large purchases |
| Furniture retail | Highly promotional | Discounting is protecting volume but weakening margins |
| Manufacturing | Uneven | Export-oriented factories face changing tariffs and order patterns |
| Housing activity | Constrained in key markets | Sofas, dining sets, bedrooms and storage remain exposed |
| Hospitality and projects | Selectively resilient | Hotels, resorts and institutional projects offer opportunities |
| Global trade | More resilient than expected overall | Gains are uneven and do not automatically translate into furniture growth |
| Freight and insurance | Volatile | Conflict-related rerouting and risk premiums complicate landed costs |
| Raw materials and energy | Uncertain | Manufacturers need shorter quotation-validity periods and stronger controls |
| Regulation | Increasing | EUDR, chemical limits, testing and traceability require greater documentation |
| E-commerce | Essential but expensive | Businesses need accurate data, efficient fulfilment and credible reviews |
| Used and refurbished furniture | Growing relevance | Value-conscious customers are considering alternatives to new products |
| Business confidence | Cautious | Companies are protecting cash and postponing expansion |
| 2027 outlook | Gradual and uneven | Housing, interest rates, conflict and consumer confidence will determine recovery |
The Global Picture: Trade Is Holding Up Better Than Confidence
The wider trade environment has proved more resilient than many businesses feared at the beginning of 2026.
The World Trade Organization raised its forecast for global merchandise-trade volume growth to 3.9% for 2026, compared with a March projection of 1.9%, and expects a further increase of 4.1% in 2027. The improvement has been supported partly by strong investment in artificial-intelligence infrastructure and the ability of supply chains to adjust to Middle East disruption. However, the WTO also warned that the benefits are uneven and that transport services have been affected by reorganised shipping routes and higher freight costs.
Furniture companies should not interpret stronger aggregate trade as evidence that household-furniture demand has recovered.
Global trade figures include high-growth technology, machinery and industrial categories. Furniture remains unusually dependent on:
- Home purchases and relocations
- Residential construction
- Consumer confidence
- Mortgage affordability
- Household disposable income
- Retail credit
- Tourism and commercial projects
- Replacement cycles
These demand drivers remain inconsistent.
The result is a two-speed economy: trade may expand overall while furniture retailers and manufacturers continue struggling with weak orders in particular markets.
United States: Housing Remains the Critical Furniture Indicator
The United States continues to be one of the most important markets for global furniture exporters, particularly manufacturers in Vietnam, Mexico, China, Malaysia, Indonesia and other Asian production centres.
However, the housing channel remains under pressure.
The latest U.S. Census Bureau data available on November 17 show that seasonally adjusted single-family housing starts fell to an annualised rate of 859,000 in September, 4.6% below the revised August estimate. The September estimate of new houses available for sale stood at 476,000. October housing-start data are scheduled for release on November 18, after this report’s publication.
This matters because housing turnover frequently triggers purchases across multiple furniture categories:
- Upholstery
- Mattresses and beds
- Dining furniture
- Bedroom furniture
- Storage
- Home-office furniture
- Outdoor furniture
- Decorative accessories
When buyers postpone moving, existing homeowners may also postpone major furnishing decisions.
What the U.S. market means for exporters
Export manufacturers cannot depend only on a general American recovery narrative. They need to examine:
- Which price segments remain active
- Whether customers are reducing inventory
- Which retailers are closing stores
- How tariffs affect landed costs
- Whether orders are moving between sourcing countries
- Which categories are gaining online
- How quickly retailers are paying suppliers
Volume without margin or secure payment is not healthy growth.
Europe: Retail Weakness Meets Regulatory Transformation
Europe presents a complicated picture.
Eurostat reported that retail-trade volume declined by 0.7% in the euro area and 0.6% across the EU in September 2026 compared with August. Compared with September 2025, retail sales were still slightly higher—0.4% in the euro area and 0.9% across the EU—indicating a subdued rather than uniformly collapsing consumer market. Industrial production increased by 0.2% in the euro area and 0.5% in the EU in September.
Furniture companies are simultaneously facing:
- Weak consumer confidence
- Energy and labour costs
- Import competition
- Retail consolidation
- Sustainability expectations
- Chemical requirements
- Traceability rules
- Extended producer responsibility
- Circular-economy pressure
A warning from the exhibition economy
One symbolic development is the cancellation of the planned January 2027 edition of imm cologne, after the organiser acknowledged that efforts to reposition the event had not secured sufficient industry support. The decision illustrates the pressure facing traditional trade-fair models as exhibitors reconsider costs, audiences and measurable return on investment.
This does not mean furniture fairs are becoming irrelevant. It means organisers must provide clearer commercial value through:
- Qualified buyers
- Export connections
- Digital discovery
- Market intelligence
- Networking
- Media visibility
- Year-round engagement
The EUDR Deadline Is Becoming Immediate
For wood furniture, components and related products entering or leaving the European Union, the EU Deforestation Regulation is no longer a distant policy discussion.
The European Commission says the regulation will begin applying from December 30, 2026 for large and medium-sized operators and for micro and small operators already covered by the EU Timber Regulation. Other micro and small operators are scheduled to follow from June 30, 2027.
Businesses placing covered products on the EU market—or exporting them—must demonstrate that the products are deforestation-free and comply with relevant legislation in the producing country.
Furniture exporters should urgently examine:
- Timber species
- Country and region of harvest
- Supplier documentation
- Geolocation information
- Chain of custody
- Due-diligence responsibilities
- Product classification
- Data retention
- Customer reporting requirements
A general statement that timber is “sustainable” will not replace the required due-diligence process.
Formaldehyde Rules Raise the Compliance Standard
New EU restrictions concerning formaldehyde emissions from furniture and wood-based products began applying on August 6, 2026.
The regulation establishes a concentration limit of 0.062 mg/m³ for furniture and wood-based articles under the prescribed test conditions, subject to stated exemptions. Products exclusively intended for outdoor use under foreseeable conditions are among the exemptions identified in the regulation.
Manufacturers using:
- Particleboard
- Medium-density fibreboard
- Plywood
- Laminated panels
- Adhesives
- Coatings
- Composite wood components
must ensure that supplier declarations correspond to the finished product and applicable test method.
Regulation is moving furniture manufacturing from informal material descriptions toward traceable technical evidence.
China: Furniture Demand Has Weakened Sharply After Earlier Policy-Supported Growth
China remains central to the global furniture ecosystem as a manufacturer, exporter, supplier of components and enormous domestic market.
The current domestic demand picture is difficult.
Official Chinese data show that retail sales in the furniture category fell 3% year on year in September 2026 and were down 4.7% during the first nine months of the year. This represents a significant reversal from the strong policy-supported growth recorded in 2025.
China’s broader October data also indicated weaker retail and manufacturing momentum, with the property downturn continuing to affect household wealth and spending confidence.
Implications for the world furniture market
A weaker Chinese domestic market can produce several international effects:
- Manufacturers may pursue exports more aggressively.
- Price competition may intensify.
- Excess capacity may pressure factory margins.
- Global buyers may obtain lower quotations.
- Trade-defence measures may increase.
- Chinese companies may invest more heavily in overseas production and brands.
- Suppliers may face longer payment cycles and tighter negotiations.
China will remain a major furniture force, but the emphasis may shift further from domestic consumption toward export competitiveness, automation, intelligent manufacturing and international expansion.
Southeast Asia: Manufacturing Strength, Export Pressure and Diversification
Southeast Asia remains one of the most strategically important furniture-producing regions.
Vietnam has strengthened its role in U.S. sourcing, while Malaysia, Indonesia and Thailand continue competing across wood furniture, upholstered furniture, outdoor products, components and contract manufacturing.
However, dependence on a small number of major markets creates vulnerability.
Malaysia’s furniture exports to the United States fell 19.2% to RM3.77 billion during January–September 2026, according to figures reported by Bernama from MATRADE. The agency is seeking new opportunities in Africa, Latin America and Central Asia as part of a broader export-diversification strategy. The same report placed Vietnam and Mexico ahead of China by share of the U.S. furniture-import market.
Malaysia’s strategic challenge
Malaysia retains meaningful advantages:
- Rubberwood expertise
- Established export manufacturers
- Multilingual commercial capability
- Port connectivity
- Regional access
- Contract-manufacturing experience
- Strong hospitality and project-furniture potential
But the industry must confront:
- Labour costs
- Automation requirements
- Compliance costs
- Currency volatility
- U.S. market dependence
- Limited consumer-brand recognition
- Competition from Vietnam and China
- Weak digital visibility among SMEs
- Shortage of structured company and product data
Diversification must mean more than attending exhibitions. Manufacturers need market-specific catalogues, compliance preparation, local partners, after-sales planning and verifiable digital identities.
Global Retail: Discounting Is Intensifying
Furniture retail remains highly promotional as companies attempt to stimulate cautious consumers and move ageing inventory.
Industry reporting from the United Kingdom indicates that more than 115,000 furniture and homeware products were advertised at discounts of at least 70% ahead of Black Friday, according to uFurnish data. The number of British furniture retailers has also declined for a fourth consecutive year, with the market losing roughly one in six retailers over the past decade.
Aggressive discounting can generate traffic, but it creates several risks:
- Margin erosion
- Reduced brand value
- Customers delaying purchases
- Conflict with dealers
- Difficulty returning to regular prices
- Cash-flow pressure after fulfilment costs
- Confusion between genuine clearance and permanent promotion
Retailers must distinguish between:
- Strategic clearance of discontinued inventory
- Short-term customer acquisition
- Promotional pricing supported by suppliers
- Uncontrolled discounting used to compensate for weak differentiation
The fourth category is the most dangerous.
IKEA’s Results Reflect the Wider Consumer Challenge
IKEA’s global retail sales reportedly fell 2% to €43.8 billion in the financial year ending August 2026, with weakness in China and the Middle East offsetting growth in Europe and Latin America.
The company has responded with a major price-reduction programme covering more than 1,000 products, while warning that geopolitical turmoil and weak confidence may continue affecting the market into 2027. ft.com
The importance of this development extends beyond one retailer.
When the world’s largest furniture retail system experiences price sensitivity, it indicates that consumers across multiple markets are actively comparing:
- Price
- Delivery costs
- Product longevity
- Space efficiency
- Resale value
- Repairability
- Financing
- Immediate availability
Furniture brands cannot assume that aspiration alone will justify a premium. They must demonstrate measurable value.
Upholstery and Bedding: Scale Is Increasing, but Costs Remain Heavy
Large upholstery and bedding companies are using acquisitions, capital markets and regional expansion to build scale.
Recent industry reports show:
- Man Wah achieved stronger sales in the United Kingdom and continental Europe, although rising costs pressured profit.
- HTL raised approximately S$8.6 million through a share placement after its secondary Singapore listing.
- Somnigroup reported third-quarter sales of $2.35 billion following its acquisition of Leggett & Platt, while statutory profit declined.
The pattern is important: revenue growth does not necessarily produce stronger earnings.
Upholstery and bedding companies face substantial exposure to:
- Foam and chemical inputs
- Textiles and leather
- Steel mechanisms
- Freight volume
- Warehousing
- Returns
- Warranty claims
- Retail credit
- Delivery labour
Companies must examine contribution margin rather than celebrating turnover alone.
Middle East Conflict: The Furniture Impact Travels Through Shipping, Energy and Confidence
Ongoing Middle East conflict remains one of the largest external risks facing the global furniture supply chain.
UN Trade and Development has reported disruption to shipping and energy flows around the Strait of Hormuz, with higher marine-fuel costs, tanker freight rates and war-risk insurance premiums affecting international supply chains. UNCTAD also notes that more than 80% of world merchandise trade by volume moves by sea, meaning disruption at critical chokepoints can spread quickly through freight, insurance, energy and household costs.
Direct consequences for furniture businesses
Freight uncertainty
Container routes can change with limited notice, creating:
- Longer transit times
- Port congestion
- Equipment shortages
- Higher insurance charges
- Unreliable delivery schedules
- Greater working-capital requirements
Energy and manufacturing costs
Furniture production depends on electricity, fuel, coatings, foam, plastics, metals, glass and packaging. Higher energy costs can move across the entire cost structure.
Hospitality and tourism disruption
The Gulf is a major centre for:
- Hotel development
- Luxury residential projects
- Retail interiors
- Restaurants
- Airlines
- Tourism
- Large infrastructure programmes
Conflict may delay private decisions and reduce travel, even when government-backed projects continue.
Quotation risk
A manufacturer offering a fixed delivered price for several months may absorb unexpected increases in freight, insurance or input costs.
Businesses should establish:
- Clear quotation-validity periods
- Freight-adjustment provisions
- Alternative routing plans
- Force-majeure language
- Customer communication protocols
- Sourcing alternatives
- Additional delivery buffers
Russia–Ukraine War Continues to Affect Materials and European Confidence
The Russia–Ukraine war remains another structural source of uncertainty.
Its furniture-industry effects include:
- Energy-price exposure
- Timber and panel sourcing concerns
- Trade restrictions
- Currency volatility
- Reconstruction uncertainty
- Consumer caution in affected European markets
- Changing transport routes
The eventual reconstruction of Ukraine could generate substantial future demand for housing, schools, healthcare, public facilities and commercial interiors. However, businesses should not treat future reconstruction as immediate revenue. Safety, financing, procurement rules and political conditions will determine when opportunities become commercially accessible.
Hospitality and Contract Furniture Offer Better Pockets of Demand
Residential furniture is closely tied to household confidence. Contract furniture operates under a different demand structure.
Hotels, resorts, restaurants, offices, schools, healthcare facilities and public buildings must continue:
- Replacing damaged furniture
- Renovating interiors
- Meeting safety requirements
- Adapting to new operating formats
- Improving accessibility
- Reconfiguring spaces
- Preparing for tourism demand
This creates opportunity in:
- Commercial seating
- Hotel bedrooms
- Outdoor hospitality furniture
- Banqueting furniture
- Restaurant tables and chairs
- Office furniture
- Healthcare furniture
- Educational furniture
- Institutional storage
- Public-area furniture
However, contract buyers increasingly demand:
- Test reports
- Material traceability
- Warranty commitments
- Replacement availability
- Fire-performance documentation
- Installation capability
- Project references
- Lifecycle-cost information
Manufacturers attempting to enter contract markets must improve technical documentation, not simply create a separate catalogue.
Office Furniture: Hybrid Work Has Not Eliminated Demand—It Has Changed It
Office furniture demand is shifting from mass workstation installation toward more varied workplace requirements.
Growth opportunities include:
- Ergonomic seating
- Collaborative spaces
- Meeting pods
- Acoustic furniture
- Flexible workstations
- Training rooms
- Reception and waiting areas
- Home-office products
- Technology-integrated furniture
- Refurbished office furniture
Employers are becoming more selective about space. Fewer desks do not necessarily mean less investment per employee. Companies may allocate more budget to ergonomics, collaboration, acoustics and employee experience.
At the same time, certification and product testing are becoming more important, particularly for work chairs, desks, storage systems and institutional furniture.
Outdoor Furniture: Climate Performance Is Becoming a Selling Point
Outdoor furniture continues benefiting from hospitality, residential balconies, restaurants, resorts and public-space investment.
But buyers are becoming more informed about climate suitability.
They increasingly evaluate:
- UV resistance
- Corrosion resistance
- Water drainage
- Cushion performance
- Wind exposure
- Fabric colourfastness
- Repairability
- Replacement parts
- Commercial load requirements
- Maintenance cost
Products designed for a dry European garden may not perform equally well in tropical humidity, Gulf heat or coastal salt exposure.
Market success increasingly depends on matching specifications to climate rather than selling one global construction as universally suitable.
E-Commerce: Discovery Is Growing, but Economics Remain Difficult
Online furniture sales continue changing how customers compare products, prices and reviews.
Yet furniture e-commerce carries high costs:
- Bulky delivery
- Damage risk
- Returns
- Assembly
- Last-mile scheduling
- Reverse logistics
- Customer-service requirements
- Product-photography costs
- Marketplace commissions
The winners are likely to be businesses that provide:
- Complete dimensions
- Accurate colour representation
- Material descriptions
- Room-scale visualisation
- Delivery details
- Assembly information
- Genuine reviews
- Replacement-part support
- Clear returns policies
Digital success is not simply uploading a photograph and price.
Circular Furniture Is Moving Closer to the Mainstream
Economic pressure and sustainability concerns are strengthening interest in:
- Used furniture
- Refurbishment
- Repair
- Rental
- Resale
- Take-back programmes
- Remanufacturing
- Component replacement
This trend creates both competition and opportunity.
Entry-level new furniture increasingly competes with better-quality pre-owned products. At the same time, manufacturers and retailers can create revenue through repair services, trade-ins, certified resale and spare parts.
The strategic question is changing from:
“How can we sell one new product?”
to:
“How can we earn value throughout the product’s useful life?”
Regional Outlook
North America
Condition: Cautious and price-sensitive.
Main constraints: Housing affordability, financing costs, tariffs, retailer consolidation and excess promotion.
Opportunities: Replacement furniture, mattresses, outdoor living, office refurbishment, logistics improvement and nearshoring.
Europe
Condition: Subdued demand with heavy regulatory pressure.
Main constraints: Consumer confidence, energy, labour, sustainability compliance and import competition.
Opportunities: Premium design, circular furniture, contract markets, repairability, low-emission products and traceable materials.
China
Condition: Weak domestic furniture retail alongside continued manufacturing power.
Main constraints: Property slowdown, consumer caution and excess capacity.
Opportunities: Smart manufacturing, export development, original design, domestic replacement demand and furniture tourism.
Southeast Asia
Condition: Strong production base facing export-market pressure.
Main constraints: U.S. dependence, tariffs, labour, compliance and intense regional competition.
Opportunities: Diversification into Africa, Central Asia, Latin America, the Middle East and intra-Asian markets.
Middle East
Condition: Large project pipeline but elevated regional risk.
Main constraints: Conflict, shipping, insurance, tourism disruption and procurement uncertainty.
Opportunities: Hospitality, luxury residential, public projects, offices, tourism infrastructure and replacement furniture.
Africa
Condition: Fragmented but structurally promising.
Main constraints: Purchasing power, financing, logistics, imports and informal distribution.
Opportunities: Urbanisation, housing, education, healthcare, local manufacturing and regional trade.
Latin America
Condition: Diverse, locally driven markets with export potential.
Main constraints: Currency fluctuations, credit costs and import barriers.
Opportunities: Local manufacturing, wood furniture, e-commerce, hospitality and regional distribution.
The Major Risks Entering 2027
Furniture businesses should prepare for at least ten major risks:
- Prolonged weakness in residential property activity
- Further escalation of Middle East conflict
- Freight and insurance volatility
- Tariff or trade-policy changes
- Aggressive retail discounting
- Customer and distributor insolvency
- Regulatory non-compliance
- Raw-material and energy shocks
- Excessive dependence on one country or buyer
- Digital invisibility despite strong capabilities
These risks are interconnected.
For example, conflict can increase freight and energy costs. Higher prices can weaken consumer demand. Weak demand can drive discounting. Discounting can compress margins and increase insolvency risk.
Management must evaluate the entire chain rather than monitoring each issue independently.
Where the Next Growth Could Come From
The strongest opportunities are likely to emerge from specific needs rather than general market expansion.
Promising areas include
- Hospitality renovation
- Tourism infrastructure
- Healthcare furniture
- Educational furniture
- Senior-living furniture
- Compact urban furniture
- Ergonomic office seating
- Outdoor commercial furniture
- Rental-property furnishing
- Repair and refurbishment
- Modular systems
- Accessible furniture
- Sustainable and traceable wood products
- Digital product passports
- Furniture logistics and installation
- Cross-border B2B discovery
- Emerging-market distribution
Manufacturers should avoid assuming that a growing category automatically guarantees profitability. Every opportunity must be tested against logistics, certification, payment risk and competitive intensity.
What Furniture Businesses Should Do Now
Manufacturers
- Reduce dependence on one export market.
- Control bills of materials and supplier changes.
- Prepare EUDR and chemical-compliance documentation.
- Analyse profitability by customer and model.
- Build market-specific product ranges.
- Publish production capabilities and certifications.
Retailers
- Stop using permanent discounting as the primary strategy.
- Identify profitable stock and aged inventory separately.
- Strengthen local search and customer retention.
- Improve delivery communication.
- Develop repair, trade-in or resale options.
- Maintain accurate product availability.
Suppliers
- Provide technical data and traceability.
- Offer realistic lead times.
- Help customers prepare compliance evidence.
- Monitor customer credit risk.
- Develop alternative materials and components.
Designers and service providers
- Demonstrate completed projects.
- Publish specialised expertise.
- Explain measurable project value.
- Build partnerships across procurement, installation and logistics.
TFT Editorial Assessment: Restructuring, Not Recovery
The global furniture industry is not entering 2027 from a position of complete stability.
The housing-led consumer market remains under pressure. Retail discounting is widespread. Compliance costs are increasing. Middle East conflict continues affecting freight, insurance and confidence. China’s domestic furniture demand has weakened, while Southeast Asian exporters are searching for greater market diversification.
Yet the industry is not without momentum.
Global trade has remained resilient. European industrial production improved modestly in September. Hospitality and institutional demand continue offering opportunities. Manufacturers are investing in new markets, capital and product development. Circular services, technology, e-commerce and specialised contract categories are creating new commercial models.
The decisive factor will be adaptability.
The businesses most likely to emerge stronger are those that can:
- Control cash
- Protect margins
- Diversify markets
- Document compliance
- Shorten development cycles
- Maintain customer trust
- Communicate genuine news
- Become discoverable through search and AI
- Build partnerships across the ecosystem
The Global Furniture Ecosystem Needs Better Intelligence
The furniture industry extends far beyond finished products. It includes manufacturers, component suppliers, material companies, retailers, designers, logistics providers, installers, testing laboratories, technology companies, repairers, artisans and professional services.
Yet the ecosystem remains fragmented.
Thousands of credible businesses are difficult to find. Product and company data remain inconsistent. Market intelligence is unevenly distributed. Customer experiences are scattered across disconnected platforms.
The role of The Furniture Times is to report, connect and explain these developments across countries and categories.
TFT tells their story. FISE helps the world find them. FurniReviewology helps the world trust them.
As the industry enters another uncertain year, visibility must be treated as infrastructure—not decoration.
A business cannot respond to global opportunity if buyers do not know it exists.