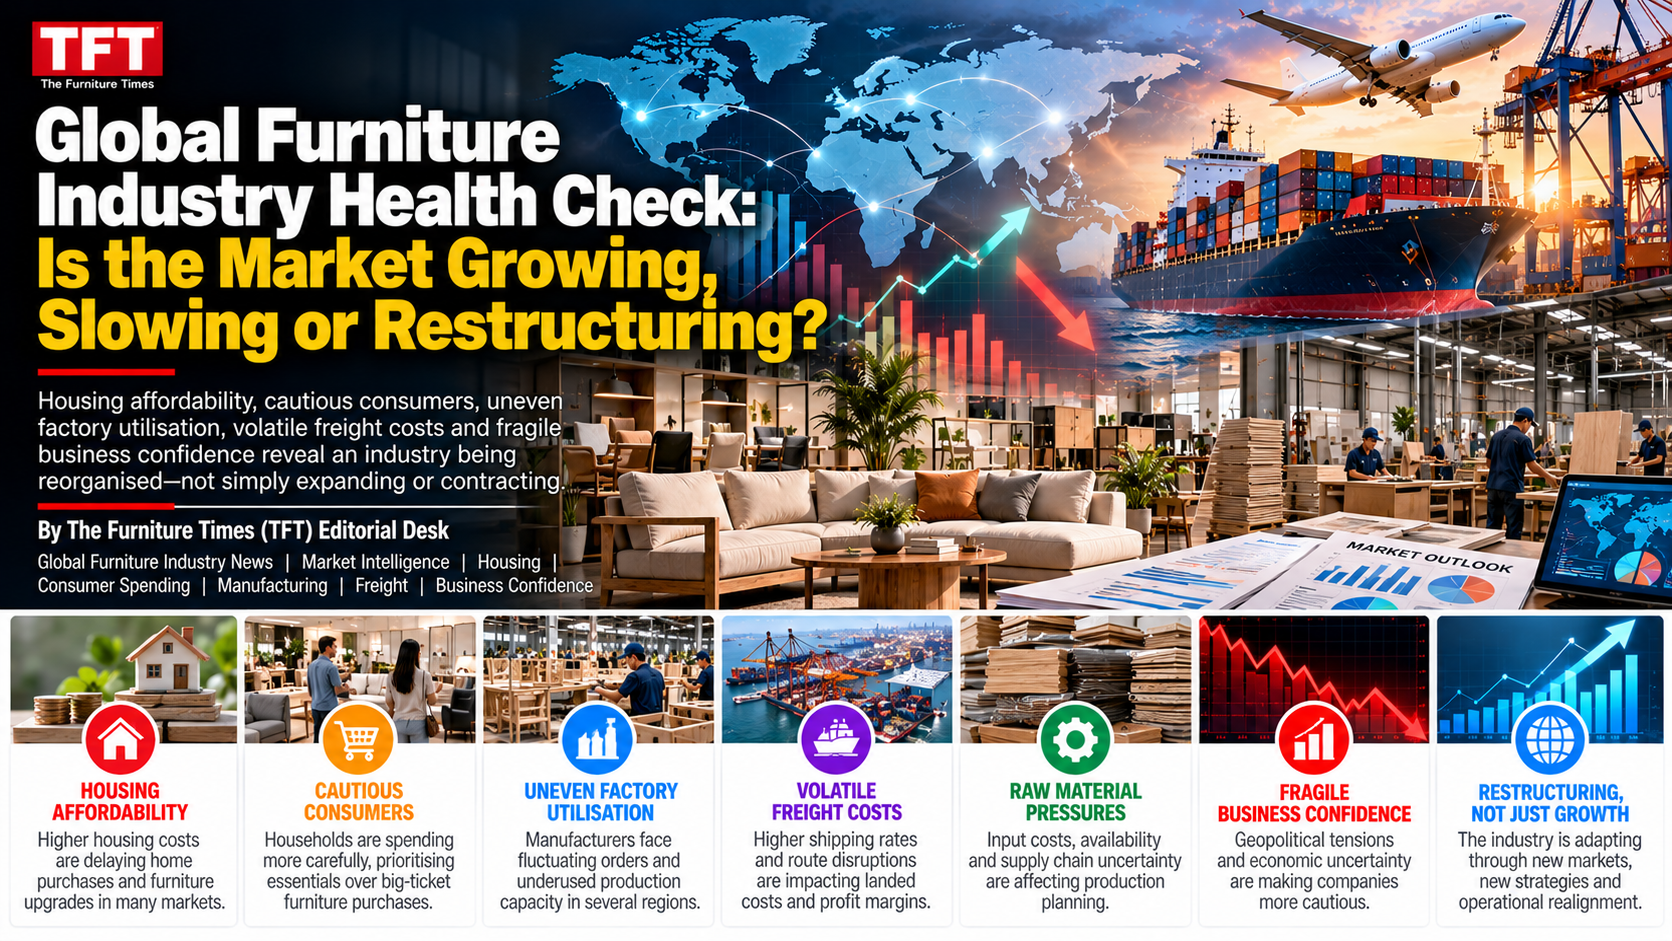
Global Furniture Industry Health Check: Is the Market Growing, Slowing or Restructuring?
Housing affordability, cautious consumers, uneven factory utilisation, volatile freight costs and fragile business confidence reveal an industry being reorganised—not simply expanding or contracting
By The Furniture Times (TFT) Editorial Desk | Global Furniture Industry News | Market Intelligence | Housing | Consumer Spending | Manufacturing | Freight | Business Confidence
The global furniture industry is not experiencing one uniform market cycle.
In some countries, furniture consumption is growing because of urbanisation, population expansion, hotel construction, public investment and rising middle-income demand. In others, high mortgage costs, weak housing transactions, expensive consumer credit and declining confidence are suppressing sales.
Some factories are operating below capacity and competing aggressively for orders. Others are investing in automation, regional production and specialised products. Some retailers are closing stores, while value-focused chains, digital platforms and well-positioned brands continue expanding.
The most accurate conclusion from The Furniture Times’ latest industry health check is therefore:
The global furniture market is neither simply growing nor universally slowing. It is undergoing a major structural reorganisation.
The sector is separating into stronger and weaker regions, scalable and outdated production models, trusted and invisible brands, efficient and overstocked retailers, and businesses prepared for volatility versus those waiting for the old market to return.
Global furniture consumption is expected to record only modest growth through 2027. At the same time, the broader global economy and merchandise trade are forecast to expand. This divergence suggests furniture will participate in economic recovery, but at a slower and more selective pace than technology-led sectors.
The industry’s health must therefore be assessed through five interconnected indicators:
- Housing demand
- Consumer spending
- Factory utilisation
- Freight and logistics costs
- Business confidence
No single market-size estimate can provide a complete diagnosis.
TFT Global Furniture Health Check
| Indicator | Current condition | Direction | TFT assessment |
|---|---|---|---|
| Housing affordability | Weak in many mature markets | Under pressure | Major constraint on residential furniture |
| Housing transactions | Uneven by country | Gradual stabilisation in selected markets | Recovery remains fragile |
| Consumer spending | Growing selectively | Cautious | Essential and value products outperform |
| Furniture retail | Highly competitive | Consolidating | Weak operators remain vulnerable |
| Factory utilisation | Uneven and frequently below potential | Restructuring | Excess capacity is increasing price pressure |
| Furniture exports | Shifting between destinations | Diversifying | New opportunities, higher trade risk |
| Ocean freight | Expensive and volatile | Uncertain | Major landed-cost risk |
| Energy and materials | Elevated and conflict-sensitive | Volatile | Margin pressure remains |
| Business confidence | Slightly improving in some economies | Fragile | Investment is selective |
| Digital commerce | Continuing to expand | Growing | More reach but stronger price competition |
| Hospitality and contract furniture | Project-driven | Selectively positive | Gulf and Asian markets offer opportunities |
| Industry employment | Skills shortages alongside layoffs | Rebalancing | Demand for technical skills is rising |
| Overall market | Not collapsing, not booming | Restructuring | Selective recovery with consolidation |
Housing Is Still the Furniture Industry’s Most Important Demand Engine
Furniture demand is closely connected to housing.
When people buy a home, move into a rental property, form a household or renovate an existing residence, they purchase beds, sofas, wardrobes, dining sets, storage, mattresses, home-office products and outdoor furniture.
When housing activity weakens, furniture purchases are frequently delayed.
The OECD reports that housing prices have eased from their pandemic-era peaks in many countries, but high borrowing costs continue to place homeownership beyond the reach of many households. Renters are also facing difficult affordability conditions, particularly in major cities.
This creates a mixed demand environment.
A household may need new furniture but lack the financial confidence to buy it. Consumers may continue using existing products, buy only essential items, select lower price points or purchase through instalment plans.
Furniture categories most exposed to weak housing transactions
- Complete bedroom sets
- Large sectional sofas
- Dining collections
- Built-in wardrobes
- Kitchen systems
- Premium outdoor furniture
- Decorative occasional furniture
- Whole-home furnishing packages
Categories that may remain more resilient
- Mattresses
- Beds
- Storage
- Home-office furniture
- Children’s furniture
- Small dining sets
- Multifunctional products
- Ready-to-assemble furniture
- Replacement seating
- Rental-property furniture
The furniture industry should not track house prices alone. It should follow transaction volume, mortgage approvals, building completions, rental turnover and household formation.
A market with rising house prices but very few transactions may generate less furniture demand than a moderately priced market with high movement and construction activity.
Housing Affordability Is Changing Product Design
The affordability problem is not only reducing sales. It is changing the furniture customers require.
Younger consumers are remaining in rented accommodation for longer. Families are living in smaller urban homes. International workers, students and mobile professionals often expect to relocate.
These conditions support demand for furniture that is:
- Compact
- Modular
- Multifunctional
- Easy to assemble
- Easy to move
- Replaceable by component
- Suitable for rental properties
- Available quickly
- Reasonably priced
Large furniture designed for permanent suburban homes will remain important, but manufacturers must recognise the growth of temporary and flexible living.
A product may now need to work as both a dining table and workspace. A sofa may need integrated storage or a sleeping function. Wardrobes may need to be modular and reconfigurable.
Housing pressure is therefore creating innovation opportunities even while restricting traditional furniture expenditure.
North American Housing: Demand Exists, but Affordability Controls Timing
The United States remains one of the most important furniture consumption and import markets.
Its furniture performance is strongly influenced by:
- Mortgage rates
- Existing-home sales
- New construction
- Consumer credit
- Employment
- Household formation
- Tariffs
- Retail inventory
When existing-home transactions slow, furniture demand can weaken because fewer households are moving. However, housing shortages, population shifts and new construction can still generate regional opportunities.
The market is likely to remain divided.
Affordable furniture, mattresses, storage, outdoor products and replacement purchases may remain active. High-value discretionary furniture can experience longer decision cycles.
Retailers must also contend with renewed inflation pressure. US consumer prices rose 3.7% year over year in September 2026, while higher fuel costs increased expectations that restrictive monetary conditions could continue.
If interest rates remain high, the effect reaches furniture twice: housing becomes less affordable, and consumer financing becomes more expensive.
Europe: Housing and Consumer Caution Continue to Restrain Demand
Europe remains a major furniture production and consumption region, but the market is under structural pressure.
Consumers in several European countries remain cautious because of:
- Energy costs
- Economic uncertainty
- High rents
- Mortgage pressure
- War in Ukraine
- Ageing populations
- Slow housing development
- Competing expenditure on travel and services
European furniture demand is expected to recover selectively rather than rapidly.
The strongest opportunities may appear in:
- Hospitality refurbishment
- Healthcare and elderly-care furniture
- Compact urban furniture
- Sustainable products
- Renovation
- Replacement furniture
- Commercial interiors
- Circular and refurbished furniture
Manufacturers depending on high-volume mid-market household furniture face stronger import competition and weaker pricing power.
Premium design companies can defend margins through identity and originality, while value retailers can compete through scale. The middle of the market remains the most exposed.
China’s Property Challenge Continues to Affect Furniture
China remains the world’s most powerful furniture-manufacturing ecosystem, but domestic demand is affected by the prolonged property downturn.
The International Monetary Fund expects Chinese economic growth to slow further in 2027 and has called for stronger measures to support domestic consumption and restore confidence in the property sector.
Industry reporting indicates that furniture retail sales among larger Chinese enterprises fell during the first half of 2026, demonstrating that overall economic expansion does not guarantee uninterrupted furniture growth.
Weak domestic demand creates consequences beyond China.
Chinese manufacturers may:
- Increase exports
- Reduce prices
- Expand through foreign platforms
- Establish overseas warehouses
- Develop international brands
- Invest in factories abroad
- Sell directly to global consumers
This puts manufacturers in Vietnam, Malaysia, Indonesia, India, Türkiye, Poland and other countries under greater competitive pressure.
China’s domestic property challenge is therefore becoming an international furniture-pricing issue.
Emerging Markets Are Carrying More of the Growth Story
India, Southeast Asia, Africa and parts of the Middle East and Latin America offer stronger long-term demand potential because of population growth, urbanisation and expanding middle-income groups.
However, emerging-market growth should not be romanticised.
Businesses must still manage:
- Weak currencies
- Import duties
- Expensive financing
- Infrastructure limitations
- Informal competition
- Regulatory uncertainty
- Uneven household income
- Political risk
The strongest opportunity may come from producing furniture within or near these markets rather than importing expensive finished products over long distances.
Regional manufacturing can improve:
- Price competitiveness
- Delivery time
- Product suitability
- Repair availability
- Local employment
- Currency resilience
- Government acceptance
The growth of emerging markets will therefore support localisation and regional production—not only international exports.
Consumer Spending: Furniture Is Competing Against Everything Else
Furniture companies often compare themselves only with competing furniture brands. The consumer does not think that way.
A household considering a new sofa may also be deciding whether to spend money on:
- Rent
- Mortgage payments
- Food
- Fuel
- Electricity
- Healthcare
- Education
- Travel
- Electronics
- Vehicle payments
- Debt repayment
- Savings
Furniture is usually a postponable purchase. Unless the existing item is broken, unsafe or connected to a move, the consumer can wait.
This makes furniture extremely sensitive to confidence.
Consumers do not need to lose their jobs before cutting furniture expenditure. Fear of possible job loss, higher interest rates or future expenses can be enough.
Consumers Are Trading Down—but Not Everywhere
The current market is producing several different spending behaviours.
Value-seeking consumers
These buyers prioritise price and may purchase:
- Flat-pack furniture
- Marketplace products
- Entry-level mattresses
- Imported furniture
- Second-hand products
- Promotional collections
Value-conscious quality buyers
These consumers still want durability but compare prices carefully. They respond to clear materials, warranties, service and reviews.
Premium buyers
Higher-income customers may remain active, especially when products offer originality, craftsmanship, sustainability or recognised design.
Commercial buyers
Hotels, offices and institutions focus on lifecycle cost, compliance, durability and service rather than only initial price.
The market is therefore not moving entirely toward cheap furniture. It is becoming more polarised.
Generic mid-priced furniture with no clear quality, design or service advantage is particularly vulnerable.
Discounting Is Masking Weakness in Furniture Retail
Retail sales can appear stronger when companies rely heavily on discounts, clearance and vouchers.
But sales revenue alone does not prove business health.
A retailer may be selling more units while earning less profit because of:
- Lower prices
- Marketplace commissions
- Advertising costs
- Delivery subsidies
- Returns
- Damage
- Financing charges
- Clearance losses
Retail performance should be evaluated through:
- Gross margin
- Net margin
- Inventory turnover
- Average order value
- Customer acquisition cost
- Delivery expense
- Return rate
- Warranty claims
- Cash conversion
- Repeat purchasing
Permanent discounting is not a sustainable growth strategy. It can create turnover while weakening the company’s ability to pay suppliers, support warranties and invest in the brand.
E-Commerce Is Expanding the Market—and Intensifying Competition
Online furniture commerce gives consumers access to more products, price comparisons and foreign sellers.
This can expand demand by making products easier to discover. It can also weaken local businesses by exposing them to competitors with fundamentally different cost structures.
Online platforms encourage:
- Price transparency
- Faster trend cycles
- Direct factory selling
- Private labels
- Consumer reviews
- Cross-border purchases
- Data-driven advertising
However, furniture e-commerce remains operationally difficult.
The product is bulky, expensive to deliver and costly to return. Online images can misrepresent colour, dimensions, materials and quality.
Companies that provide accurate specifications, realistic photography, verified reviews and strong delivery information will have an advantage over sellers relying on attractive images and low prices alone.
Factory Utilisation: The Hidden Indicator of Industry Health
Factory utilisation reveals whether a manufacturer is operating close to its practical production capacity.
A factory may own machinery capable of producing 10,000 units per month but receive orders for only 6,000. The facility is then operating at approximately 60% of its nominal capacity, although technical definitions vary.
Low utilisation creates several problems:
- Fixed costs are spread over fewer products
- Unit costs rise
- Workers and machines remain idle
- Cash flow weakens
- Price competition intensifies
- Maintenance may be delayed
- Skilled employees may leave
- Investment is postponed
Global furniture-factory utilisation is difficult to measure because the industry consists of thousands of private companies and informal workshops. There is no complete real-time global utilisation database.
Available industry signals nevertheless point to considerable excess capacity in several product categories.
These signals include:
- Aggressive factory quotations
- Shorter order books
- Export redirection
- High inventory
- Factory closures
- Reduced working hours
- Consolidation
- Manufacturers accepting smaller orders
- Increased private-label competition
Not All Furniture Factories Are Underutilised
Capacity problems are not evenly distributed.
Factories producing generic, highly substitutable products may struggle for orders. Specialised manufacturers can remain fully occupied.
Stronger categories can include:
- Hospitality project furniture
- Healthcare furniture
- Laboratory furniture
- Educational furniture
- Luxury craftsmanship
- Custom joinery
- Acoustic products
- Ergonomic seating
- Outdoor commercial furniture
- Defence and institutional furniture
The distinction is increasingly between factories selling capacity and factories selling capability.
A factory that says, “We can produce chairs cheaply,” competes against thousands of companies.
A factory that says, “We produce tested, repairable seating for hotels in humid coastal markets with dependable replacement parts,” offers a more defensible capability.
China, Europe and the United States Face Different Factory Problems
China
China has enormous manufacturing capacity, advanced supply clusters and efficient export infrastructure. Its challenge is balancing that capacity against weaker domestic property demand and changing trade relationships.
Europe
European manufacturers face high labour, energy and compliance costs. Their strengths remain engineering, design, premium production, automation and proximity to sophisticated markets.
United States
American furniture manufacturing has regional strengths but competes with imports and high labour costs. Tariffs and supply-chain concerns are encouraging selected localisation. IKEA, for example, has been increasing US production and working with regional suppliers as tariffs and logistics risks affect imports.
Southeast Asia
Vietnam, Malaysia and Indonesia benefit from export experience and supply-chain diversification. Their challenges include labour, materials, compliance, automation and dependence on external demand.
India
India possesses considerable domestic growth potential, but manufacturers must improve standardisation, testing, scale, productivity and quality systems.
Capacity Utilisation Must Be Measured by Product Line
A factory-wide average can hide serious inefficiency.
A manufacturer might have:
- Upholstery at 85% utilisation
- Woodworking at 55%
- Metal fabrication at 40%
- Finishing at 95%
- Packaging at 60%
The finishing department becomes a bottleneck while other areas remain underused.
Furniture manufacturers should monitor:
- Capacity by machine
- Capacity by department
- Labour utilisation
- Downtime
- Rework
- Material yield
- Order profitability
- Changeover time
- On-time completion
- Energy per unit
The goal is not to keep every machine running regardless of demand. Producing unwanted inventory only converts unused capacity into trapped cash.
Freight Costs Remain a Major Health Risk
Furniture is especially vulnerable to freight because of its physical volume.
A sofa, mattress, wardrobe or outdoor set can occupy a large portion of a container even when its manufacturing value is moderate.
Drewry’s World Container Index stood at approximately US$4,351 per 40-foot container in early October 2026, although route-level prices differed greatly. Shanghai-to-Los Angeles rates were reported at about US$7,624, while Shanghai-to-New York exceeded US$10,000 per 40-foot container.
Intra-Asian rates were considerably lower, with Drewry’s regional index around US$1,503 per 40-foot container in the same period.
These differences can determine which suppliers remain competitive.
A manufacturer may have a lower factory price but lose the order after freight, duty, insurance, storage and delivery are included.
Conflict Has Reintroduced Extreme Freight Volatility
Freight markets are being affected by war and insecurity around:
- The Strait of Hormuz
- The Red Sea
- The Gulf of Aden
- The Black Sea
- The Persian Gulf
The conflict involving Iran caused container rates from Asia to the United States to rise sharply during 2026. Spot rates from China to the US East Coast approached pandemic-era peaks as fuel prices, risk and shipping disruption increased.
Commercial ships have also faced attacks near the Strait of Hormuz, intensifying concerns about cargo safety, insurance and route availability.
Furniture businesses face more than the visible ocean rate.
Additional expenses may include:
- War-risk insurance
- Emergency surcharges
- Bunker adjustments
- Port storage
- Demurrage
- Detention
- Container repositioning
- Inland rerouting
- Damage
- Additional handling
- Financing during delays
Companies should calculate the complete landed cost rather than relying on the supplier’s factory price.
Freight Volatility Encourages Regionalisation
Repeated logistics shocks are causing brands to reconsider where products are manufactured and stocked.
The emerging model is not complete deglobalisation. It is selective regionalisation.
A company may use:
- Asia for large-volume production
- Eastern Europe or Türkiye for European replenishment
- Mexico for North America
- Local upholstery near final markets
- Regional warehouses for fast-moving products
- Multiple factories for strategic categories
Regionalisation can reduce transit time and supply disruption, but local production may cost more.
The correct calculation should include:
- Factory price
- Freight
- Duties
- Inventory financing
- Delivery time
- Damage risk
- Minimum order quantity
- Currency exposure
- Lost-sales risk
- Responsiveness
The lowest manufacturing price is not always the lowest commercial cost.
Business Confidence: Stable Enough to Operate, Too Fragile for Careless Expansion
Business confidence is neither collapsing nor strongly positive.
The OECD’s business-confidence indicator has remained close to its long-term neutral level, while G20 growth slowed modestly during the second quarter of 2026. OECD inflation also rose as energy prices increased.
Consumer confidence has improved in parts of the advanced world, but economic projections remain exposed to conflict, energy prices, tariffs and financial-market volatility.
Furniture executives are therefore investing selectively.
They are more likely to approve projects that:
- Reduce energy use
- Improve productivity
- Lower labour dependency
- Support smaller batches
- Improve inventory accuracy
- Strengthen direct sales
- Reduce returns
- Improve product information
- Diversify supply
- Create measurable payback
Large investments based only on optimistic market growth are more difficult to justify.
SMEs Are Less Confident Than Large Groups
Large furniture groups may have:
- Multiple markets
- Better credit access
- Negotiating power
- Internal technology teams
- Larger inventories
- Strong supplier relationships
- Recognised brands
Small and medium enterprises frequently operate with:
- Limited cash reserves
- One major customer
- One export market
- Manual processes
- Weak digital visibility
- High borrowing costs
- Limited market data
This creates a confidence gap.
A modest market slowdown can be manageable for a large group but existential for a small manufacturer or retailer.
Furniture-industry health should therefore not be evaluated only through major brands. The condition of smaller suppliers, independent retailers, installers and workshops matters because they form much of the ecosystem.
The Industry Is Restructuring Around Six Major Shifts
1. From global dependence to regional resilience
Companies are diversifying factories, suppliers, ports and warehouses.
2. From product selling to service ecosystems
Delivery, installation, repair, warranties and customer support are becoming more important.
3. From large inventory to demand-led replenishment
Retailers want less stock and more flexible production.
4. From anonymous manufacturing to visible capability
Factories need digital identities, certifications, case studies and searchable information.
5. From price-only competition to verified value
Materials, durability, safety, reviews and lifecycle cost influence purchasing.
6. From traditional search to AI-assisted discovery
Business information must be structured so search engines and AI systems can understand it.
Which Furniture Categories Appear Healthiest?
Relatively resilient
- Mattresses and sleep products
- Storage
- Healthcare furniture
- Educational furniture
- Hospitality refurbishment
- Commercial outdoor furniture
- Ergonomic seating
- Repair and refurbishment
- Rental furniture
- Modular furniture
Selectively growing
- Luxury furniture
- Smart furniture
- Sustainable furniture
- Airbnb and homestay furniture
- Small-space furniture
- Home-office products
- Senior-living furniture
- Acoustic office products
Under greater pressure
- Generic mid-market residential furniture
- Large decorative collections
- Undifferentiated imports
- High-inventory showroom formats
- Products with expensive return logistics
- Manufacturers dependent on one retailer
- Retailers relying on permanent discounts
This categorisation differs by country and should be treated as a strategic guide rather than a universal ranking.
TFT’s Market Diagnosis
Is the market growing?
Yes—in selected countries, categories and channels.
India, parts of Southeast Asia, hospitality projects, institutional furniture, online commerce, specialised manufacturing and emerging consumer markets provide growth opportunities.
Is the market slowing?
Yes—in mature housing-dependent markets, generic residential categories and businesses affected by expensive credit or weak consumer confidence.
Is the market restructuring?
Most definitely.
Supply chains, retail formats, manufacturing technology, sourcing patterns, product design, customer expectations and business discovery are all changing simultaneously.
The restructuring is more important than the short-term growth rate.
Warning Signs Furniture Companies Should Monitor
Furniture businesses should track these indicators monthly:
| Indicator | Warning sign |
|---|---|
| Order intake | Three consecutive months of decline |
| Factory utilisation | Persistent operation below sustainable capacity |
| Gross margin | Sales maintained only through discounting |
| Inventory | Stock growing faster than revenue |
| Receivables | Customers taking longer to pay |
| Freight | Quoted rates valid for shorter periods |
| Returns | Rising delivery damage or expectation mismatch |
| Customer concentration | One buyer becoming too dominant |
| Marketing | Reduced visibility and enquiry volume |
| Staff | Loss of skilled technical workers |
| Energy | Cost per unit rising despite stable output |
| Website traffic | Falling branded and high-intent visits |
| Reviews | Complaints increasing without response |
| Export exposure | Excessive dependence on one destination |
A slowdown becomes dangerous when multiple warning signs appear together.
Actions for Manufacturers
- Measure actual utilisation by production line.
- Stop producing inventory without verified demand.
- Identify unprofitable orders and customers.
- Develop alternative materials and components.
- Improve energy measurement.
- Invest selectively in automation.
- Strengthen quality documentation.
- Diversify export destinations.
- Publish factory capabilities online.
- Develop spare-parts and repair support.
- Build direct relationships with buyers.
- Protect working capital.
Actions for Retailers
- Calculate profitability after every platform and delivery cost.
- Reduce slow-moving stock.
- Improve product descriptions and dimensions.
- Use customer reviews as operational intelligence.
- Offer honest delivery windows.
- Strengthen after-sales service.
- Develop private-label products carefully.
- Avoid permanent discounting.
- Build direct customer databases.
- Use showrooms as trust and experience centres.
- Invest in local search and AI visibility.
Actions for Suppliers and Service Providers
Component manufacturers, logistics companies, designers, installers, repairers and technology firms should not wait for finished-furniture brands to discover them accidentally.
They should make their capabilities searchable by publishing:
- Categories supplied
- Materials
- Production capacity
- Locations
- Certifications
- Minimum quantities
- Export markets
- Lead times
- Technical drawings
- Project experience
- Contact information
The companies solving cost, logistics, compliance, repair or visibility problems may grow even when finished-furniture demand remains slow.
TFT, FISE and FurniReviewology: Intelligence, Discovery and Trust
The furniture industry’s restructuring increases the need for reliable information and industry-specific infrastructure.
The Furniture Times—TFT reports the developments shaping manufacturers, suppliers, retailers, designers and service providers.
Furniture Industry Search Engine—FISE helps buyers discover companies across the furniture ecosystem.
FurniReviewology supports trust through reviews, reputation and customer-experience intelligence.
The Furniture Times tells their story.
Furniture Industry Search Engine helps the world find them.
FurniReviewology helps the world trust them.
The furniture industry ecosystem is a $1 trillion industry ecosystem, but much of it remains digitally fragmented and commercially difficult to navigate.
Restructuring creates risk—but it also creates the opportunity to build a more searchable, transparent and connected global industry.
Final Verdict: The Market Is Being Rebuilt
The global furniture industry is healthier than the most pessimistic headlines suggest, but weaker than headline market-growth forecasts may imply.
Demand has not disappeared. It has moved.
It is moving:
- From mature markets toward emerging markets
- From large homes toward smaller spaces
- From generic products toward clear value
- From fixed offices toward flexible workplaces
- From new-only consumption toward repair and resale
- From distant supply chains toward regional resilience
- From anonymous factories toward visible suppliers
- From traditional advertising toward search, reviews and AI discovery
The industry is not returning to the conditions that existed before the pandemic, energy shocks, wars and digital-commerce acceleration.
It is forming a new structure.
Furniture companies should not ask only:
“When will the old market come back?”
They should ask:
“Where has demand moved, and what must we change to follow it?”
The market is growing in places, slowing in others—and restructuring everywhere.
Sources:
OECD—Housing
OECD—Business Confidence Index
OECD—Economic Outlook, September 2026
Drewry—World Container Index
Drewry—Intra-Asia Container Index
Furnilytics—Furniture Market Analytics