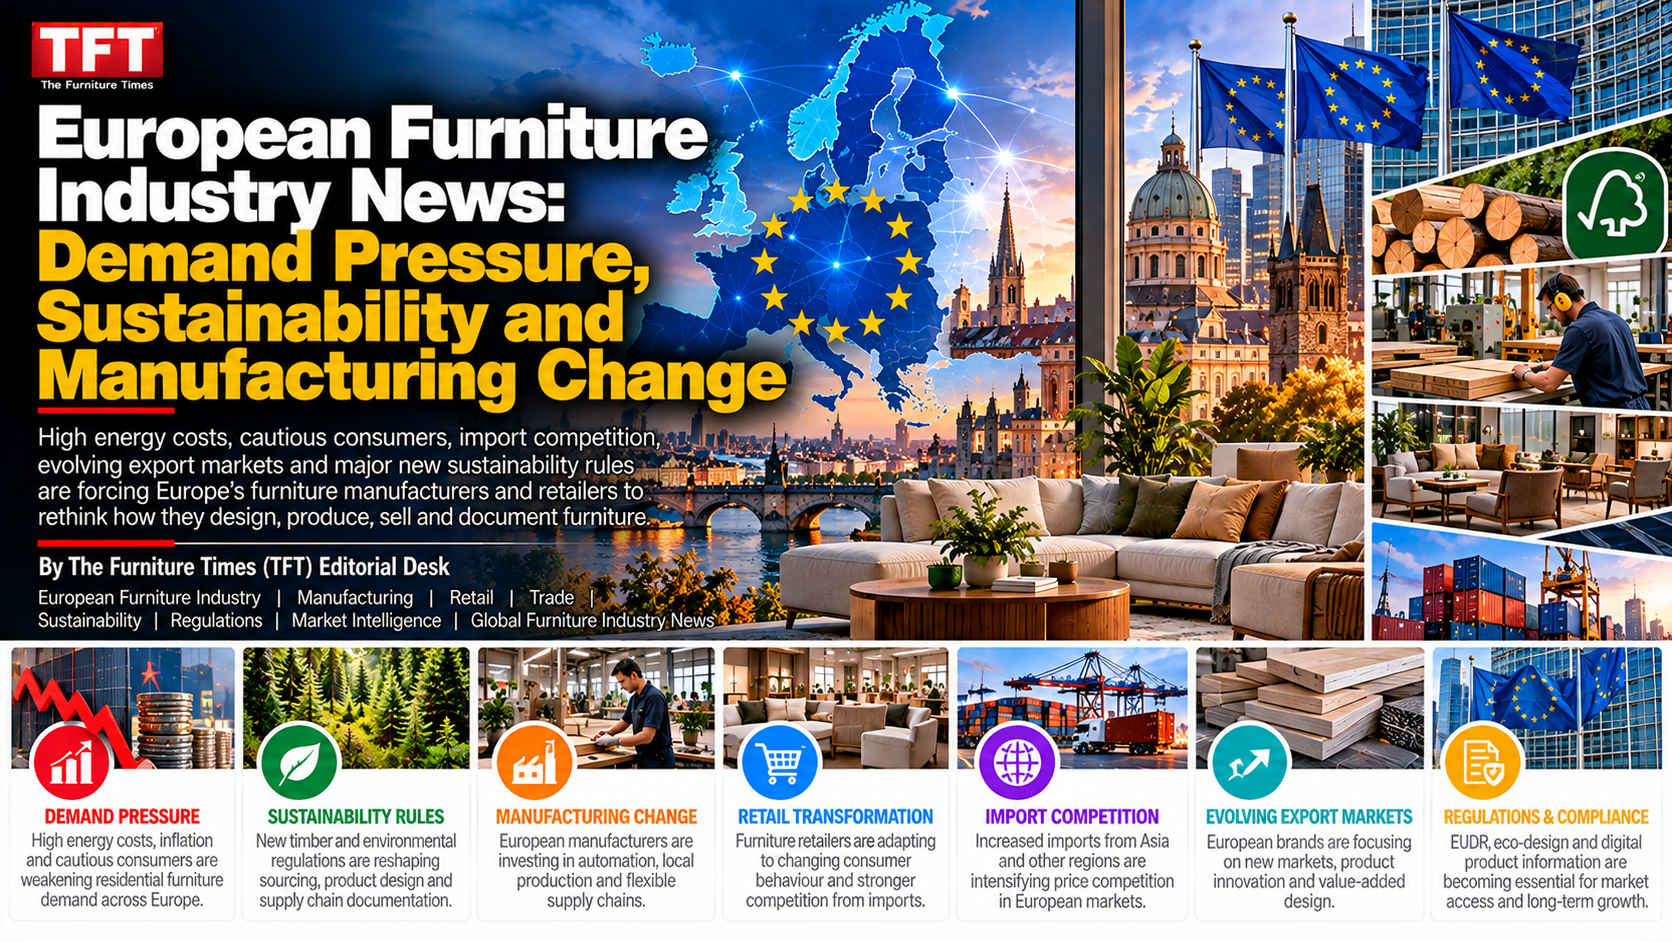
European Furniture Industry News
European Furniture Industry News: Demand Pressure, Sustainability and Manufacturing Change
High energy costs, cautious consumers, import competition, evolving export markets and major new sustainability rules are forcing Europe’s furniture manufacturers and retailers to rethink how they design, produce, sell and document furniture
By The Furniture Times (TFT) Editorial Desk | European Furniture Industry | Manufacturing | Retail | Trade | Sustainability | Regulations | Market Intelligence | Global Furniture Industry News
Europe’s furniture industry entered the final quarter of 2026 under growing pressure to change.
Household furniture demand remains subdued across several important markets. Housing affordability and limited property transactions are delaying big-ticket purchases. Manufacturers face renewed energy-price pressure, expensive labour and competition from imported products. Exporters are navigating tariffs, geopolitical disruption and changing international demand.
At the same time, Europe is advancing one of the world’s most ambitious product-sustainability and traceability programmes.
The European Union Deforestation Regulation is approaching a critical application date. The Ecodesign for Sustainable Products Regulation is preparing the way for product-level requirements involving durability, repairability and circularity. Digital Product Passport infrastructure has become operational, with furniture identified as a priority product group for future implementation.
These forces are pushing the sector beyond traditional questions of design, manufacturing cost and retail price.
Furniture companies increasingly need to answer:
- Where did the timber originate?
- What materials and components are inside the product?
- How long should the furniture last?
- Can damaged components be replaced?
- Can the item be disassembled or refurbished?
- Are environmental claims supported by evidence?
- Can product information be communicated digitally?
- Can the company remain profitable while consumers demand lower prices?
Europe continues to possess considerable furniture strengths: Italian design, German engineering, Polish manufacturing, Scandinavian aesthetics, Baltic wood processing, Spanish and Portuguese craftsmanship, and extensive retail and distribution networks.
But leadership in the next phase will depend on whether European companies can combine these traditional strengths with affordability, automation, accurate product data and circular services.
European Furniture Industry Dashboard
| Indicator | Current direction | TFT assessment |
|---|---|---|
| Residential furniture demand | Weak to stagnant | Consumers remain cautious |
| Contract and hospitality demand | Selectively positive | Offers an alternative to residential weakness |
| Energy costs | Rising and volatile | Serious risk to factory margins |
| European manufacturing | Uneven | Premium and specialised producers show greater resilience |
| Furniture imports | Competitive pressure remains high | Value and mass-market categories are exposed |
| Furniture exports | Mixed | Premium design retains international appeal, but tariffs and weak demand matter |
| Furniture retail | Highly promotional | Affordability and convenience are driving strategy |
| Retail consolidation | Increasing scrutiny | Scale may strengthen purchasing power but reduce competition |
| EUDR readiness | Urgent | December 2026 deadline approaching for many operators |
| Digital Product Passports | Infrastructure advancing | Furniture businesses should prepare their data now |
| Circular furniture | Growing strategic importance | Repair, refurbishment and resale offer new opportunities |
| Industry confidence | Cautious | Selective recovery rather than broad expansion |
European Furniture Demand Remains Under Pressure
Europe is not experiencing a uniform furniture recovery.
Available industry analysis indicates that furniture demand is likely to remain almost stagnant during 2026 as households maintain higher savings, limit discretionary purchases and shift parts of their spending toward travel, hospitality and other experiences. worldfurnitureonline.com
The reasons extend beyond furniture.
Consumers are dealing with:
- High housing costs
- Expensive mortgages
- Energy bills
- Food inflation
- Economic uncertainty
- Weak property transactions
- Concerns about employment and income
- Higher delivery and installation charges
A sofa, dining set, wardrobe or bedroom suite can often be postponed.
This makes furniture especially vulnerable when households feel financially uncertain.
Demand has not disappeared—it has become selective
Consumers still buy furniture when they:
- Move home
- Renovate
- Form a household
- Replace a failed item
- Adapt to remote work
- Furnish rental properties
- Care for older relatives
- Improve energy or space efficiency
However, purchasing decisions take longer, comparisons are more detailed and price sensitivity is stronger.
Retailers are therefore competing for fewer immediate transactions.
The European Market Is Splitting Into Three Segments
1. Value and affordability
This segment serves consumers prioritising price, immediate availability and functional performance.
It is supported by:
- Flat-pack products
- Basic storage
- Entry-level mattresses
- Compact furniture
- Promotional collections
- Self-assembly
- Online ordering
The challenge is maintaining acceptable quality while controlling freight, store and return costs.
2. Premium and design
This segment competes through:
- Original design
- Material quality
- Craftsmanship
- Customisation
- Brand heritage
- Provenance
- Professional service
Affluent consumers and high-value projects remain active, but expectations are high.
3. Service and lifecycle value
This emerging segment competes through:
- Planning
- Measurement
- Installation
- Maintenance
- Repair
- Refurbishment
- Trade-in
- Resale
- Replacement parts
Generic middle-market furniture is the most exposed. It is often too expensive to compete with entry-level products and insufficiently differentiated to command premium pricing.
Energy Costs Return as a Major Manufacturing Risk
Furniture manufacturing is energy-sensitive even where the final product is not considered energy intensive.
Factories use energy for:
- Timber drying
- Panel pressing
- CNC machining
- Metal cutting and welding
- Powder coating
- Foam production
- Textile manufacturing
- Heating
- Ventilation
- Finishing
- Packaging
- Warehousing
Europe is facing another period of elevated gas prices. Storage levels are expected to enter the winter below recent averages, while Middle East conflict has affected LNG availability and increased competition between European and Asian buyers. Analysts have warned that normal market conditions may not return quickly. reuters.com
The impact is uneven
Energy pressure is greatest for:
- Panel manufacturers
- Glass processors
- Metal suppliers
- Foam producers
- Textile mills
- Large factories with drying and finishing operations
Furniture manufacturers may experience both direct energy costs and indirect increases passed through by suppliers.
Europe’s industrial weakness
Eurozone industrial output declined again in August 2026, continuing a sequence of monthly falls as energy costs and geopolitical uncertainty affected factory activity. Production weakness was visible in France, Italy and Spain, while Germany recorded only limited improvement. wsj.com
This broader industrial environment matters to furniture because the sector depends on metals, chemicals, machinery, transport and construction.
High European Costs Are Changing Production Strategies
Manufacturers are responding to cost pressure through several strategies.
Automation
Investment is increasing in:
- CNC machining
- Automated cutting
- Edge banding
- Robotic finishing
- Digital nesting
- Automated warehouses
- Quality inspection
- Production scheduling
The objective is not simply to reduce employment. It is to reduce errors, material waste, rework and unplanned downtime.
Flexible manufacturing
Factories are moving away from large volumes of speculative stock and toward:
- Smaller production runs
- Made-to-order products
- Modular components
- Configurable finishes
- Postponed final assembly
- Standardised platforms
Nearshoring within Europe
Western European companies may source or manufacture in:
- Poland
- Romania
- Lithuania
- Latvia
- Estonia
- Bulgaria
- Croatia
- Bosnia and Herzegovina
- Serbia
- Turkey
These markets can offer lower costs and greater proximity than Asian imports, although wages, energy, logistics and compliance expenses continue rising.
Renewable energy and efficiency
Factories investing in solar power, heat recovery, efficient motors and material optimisation may gain greater cost stability.
Energy investment is therefore becoming part of competitive strategy rather than only corporate sustainability.
Imports Continue to Pressure European Manufacturers
European furniture manufacturing faces strong competition from Asia and neighbouring production regions.
Imports can offer:
- Lower factory prices
- Large production capacity
- Extensive product variety
- Mature flat-pack systems
- Integrated component supply
- Fast product development
European companies compete against China’s scale, Vietnam’s export capacity, Malaysia’s established furniture clusters, Indonesia’s natural materials, India’s emerging production and Turkey’s geographic proximity.
The landed-cost equation is changing
The lowest factory price does not always produce the lowest total cost.
Importers must consider:
- Ocean freight
- Fuel surcharges
- Insurance
- Customs duty
- Tariffs
- Warehousing
- Inventory holding
- Currency movements
- Damage
- Returns
- Long replenishment cycles
- Compliance documentation
Geopolitical disruption can make regional manufacturing more attractive, even where the factory price is higher.
Import competition remains strongest in
- Entry-level upholstery
- Flat-pack storage
- Dining furniture
- Bedroom furniture
- Outdoor furniture
- Small occasional furniture
- Home-office products
European manufacturers need a clear reason for customers to pay more.
That reason may be design, shorter lead time, customisation, repairability, provenance or project service—but it must be visible and credible.
European Exports Face a More Difficult World
Europe remains a major exporter of premium furniture, kitchens, office systems, lighting and contract interiors.
Important export strengths include:
- Italian design
- German engineering
- Scandinavian brands
- Polish production
- Spanish and Portuguese craftsmanship
- European office and contract furniture
- Woodworking machinery
- Premium kitchen systems
However, international conditions are more challenging.
Exporters face:
- US tariffs
- Weak housing markets
- High freight costs
- Currency changes
- Middle East instability
- Chinese competition
- Local-content preferences
- Project delays
Italian furniture retains a trade advantage
Italy maintained a furniture trade surplus of approximately €8.4 billion in 2025 despite a 1.2% decline in exports. Sales increased in markets including Germany, the United Kingdom and Spain, while exports to France declined. Growth in the United Arab Emirates and Turkey demonstrated the importance of diversified markets. group.intesasanpaolo.com
The results show that premium design and “Made in Italy” continue to possess international value, but even strong brands must adapt to uneven demand.
US tariff exposure
US furniture tariffs affect European exporters as well as Asian suppliers.
Previously announced measures included a 30% tariff on imported upholstered furniture and a 50% tariff on kitchen cabinets and vanities. European companies exporting these products must assess their classification, existing duty exposure and customer contracts carefully. reuters.com
Germany: Scale, Engineering and Weak Consumer Momentum
Germany is Europe’s largest industrial economy and one of its most important furniture markets.
Its strengths include:
- Large consumer base
- Kitchen furniture
- Office furniture
- Machinery
- Hardware
- Retail networks
- Engineering
- Product testing
However, German furniture demand is affected by cautious consumers, construction weakness, housing costs and high energy prices.
Germany’s broader exports fell by 0.8% in August after declining in July, while imports increased. Imports from China grew faster than German exports to China, illustrating the competitive pressure confronting the country’s industrial base. wsj.com
Retail affordability becomes central
IKEA’s European price-investment programme included reductions on more than 1,500 products in Germany. This places additional pressure on retailers and manufacturers that cannot match IKEA’s scale or operating efficiency. reuters.com
Germany’s opportunity
German companies can remain competitive through:
- Premium kitchens
- Office systems
- Senior-living furniture
- Circular services
- Automation
- Technical components
- Product testing
- Repairability
Competing directly with low-cost mass imports on price alone will be difficult.
Italy: Design Leadership Must Meet Industrial Discipline
Italy remains one of the world’s most influential furniture and interior-design centres.
Its competitive strengths include:
- Brand heritage
- Design talent
- Premium manufacturing
- Upholstery
- Lighting
- Kitchens
- Contract furniture
- Artisan production
- Global exhibitions
Italian furniture’s challenge is not cultural relevance. It is maintaining profitability while dealing with high costs and slower demand.
Contract furniture offers growth
Italian companies are well positioned for:
- Hotels
- Luxury residential projects
- Yachts
- Restaurants
- Retail interiors
- Branded residences
- Offices
Salone del Mobile’s increasing focus on the contract market reflects the strategic importance of integrated project business.
Risk for smaller Italian companies
Many highly capable Italian SMEs lack the marketing resources and digital visibility of major brands.
Their future depends on:
- International discovery
- Designer collaboration
- Structured product information
- Digital catalogues
- Verified sustainability
- Export partnerships
Italian design leadership must become digitally searchable beyond exhibition season.
Poland and Central Europe: Manufacturing Strength Under Cost Pressure
Poland has become one of Europe’s most important furniture-production and export centres.
Its advantages include:
- Proximity to major EU markets
- Large manufacturing capacity
- Woodworking skills
- Competitive cost structures
- Established supply relationships
- Road logistics
- Experience with international retailers
Poland serves both branded and private-label furniture markets.
The changing cost equation
Polish manufacturers now face:
- Wage inflation
- Energy costs
- Labour shortages
- Imported component costs
- Buyer price pressure
- Automation requirements
The country remains competitive, but it cannot rely indefinitely on lower labour costs.
Its next phase should emphasise:
- Productivity
- Original design
- Polish brands
- Automation
- Circular manufacturing
- Direct buyer access
Romania, Bulgaria and the Baltic states face similar opportunities and pressures at different scales.
Scandinavia: Sustainability Leadership Meets Affordability Pressure
Denmark, Sweden, Finland and Norway possess global reputations for:
- Functional design
- Minimalism
- Wood furniture
- Responsible materials
- Durability
- Human-centred interiors
Scandinavian design remains influential, but regional consumers face high living costs.
In 2025, Denmark had the highest overall consumer-goods and services price level in the EU, approximately 40% above the EU average. ec.europa.eu
Opportunity
Scandinavian companies can lead in:
- Circular furniture
- Furniture leasing
- Design for disassembly
- Repair systems
- Bio-based materials
- Workplace furniture
- Public procurement
- Digital Product Passports
Commercial risk
Sustainability cannot function only as a premium concept. Companies must make durable and repairable furniture accessible to a wider consumer base.
Spain and Portugal: Craft, Hospitality and Export Potential
Spain and Portugal combine:
- Woodworking
- Upholstery
- Ceramic and surface expertise
- Hospitality demand
- Design communities
- Regional export access
Tourism supports furniture procurement for hotels, restaurants, resorts and short-term accommodation.
These countries can expand through:
- Hospitality furniture
- Outdoor collections
- Natural materials
- Contract manufacturing
- Custom joinery
- Renovation projects
Energy costs and industrial weakness remain constraints, but hospitality and refurbishment offer alternatives to subdued residential demand.
The United Kingdom: A Large Import Market With Retail Pressure
The UK is outside the European Union but remains central to the wider European furniture economy.
Its market is highly exposed to:
- Imports
- Currency movements
- Housing transactions
- Consumer credit
- Delivery costs
- Retail rents
- Online competition
Retailers must balance affordability with service while manufacturers contend with energy and labour costs.
Opportunity areas
- British-made premium furniture
- Mattresses
- Contract interiors
- Senior living
- Repair and reupholstery
- Online customisation
- Small-space furniture
The UK also remains an important export destination for European furniture brands, including Italian producers.
European Furniture Retail Is Consolidating
Retail consolidation is becoming an important issue.
The European Commission has opened an antitrust investigation into XXXLutz’s proposed acquisition of German retailer Porta. The transaction could combine XXXLutz’s large European network with Porta’s approximately 140 outlets. Regulators are examining whether the deal could reduce competition in Germany, the Czech Republic, Slovakia and Poland and increase pressure on suppliers. reuters.com
Why consolidation matters
Larger retail groups can gain:
- Purchasing power
- Logistics efficiency
- Marketing scale
- Technology investment
- Strong private labels
- Better supplier terms
But consolidation can also create:
- Fewer routes to market
- Greater pressure on factory margins
- Dependence on major buyers
- Reduced assortment diversity
- Harder conditions for small brands
Manufacturers should monitor customer concentration as carefully as they monitor supplier concentration.
IKEA’s Price Cuts Reveal the Retail Reality
IKEA announced an investment of approximately €1.2 billion in European price reductions to attract cautious consumers after two years of declining revenue.
The company reduced prices across major markets, including more than 1,500 products in Germany, while also opening smaller-format stores and investing in product redesign, automation and renewable energy. reuters.com
This is not simply a promotional campaign.
It reflects several structural realities:
- Furniture affordability is under pressure.
- Consumers live in smaller homes.
- Large destination stores are no longer sufficient.
- Cost reduction must come from operations and design.
- Retailers need to reach customers closer to where they live.
Smaller retailers cannot match a €1.2 billion price programme.
They must compete through:
- Specialisation
- Local service
- Faster delivery
- Installation
- Customisation
- Product knowledge
- Independent reviews
- Repair and after-sales support
EUDR: The Immediate Compliance Challenge
The EU Deforestation Regulation is one of the most urgent issues for the wood-furniture supply chain.
The regulation covers relevant commodities and derived products listed by their classification codes. Businesses must determine whether their products fall within scope and comply with applicable due-diligence requirements. green-forum.ec.europa.eu
The amended implementation dates include:
- 30 December 2026 for large and medium operators
- 30 June 2027 for most micro and small operators
- 30 December 2026 for certain smaller operators previously covered by the EU Timber Regulation framework
Why furniture is complicated
A single furniture item may include:
- Solid wood
- Veneer
- Plywood
- MDF
- Particleboard
- Timber components
- Wooden packaging
Different materials may originate from multiple suppliers and countries.
Documentation needs
Companies should be able to connect:
Product model
→ Bill of materials
→ Timber component
→ Supplier
→ Species and origin
→ Due-diligence reference
→ Production batch
→ Shipment
The greatest risk may not be unlawful timber. It may be incomplete or inconsistent documentation.
European importers are likely to demand more information from suppliers in China, Vietnam, Malaysia, Indonesia, India and other producing countries.
Ecodesign Will Change the Meaning of Product Quality
The Ecodesign for Sustainable Products Regulation establishes a framework through which requirements can be developed for product groups.
Depending on future furniture-specific measures, relevant issues could include:
- Durability
- Reliability
- Repairability
- Upgradability
- Recycled content
- Material efficiency
- Environmental footprint
- Information requirements
- Ease of disassembly
- Recycling
The European Commission’s 2025–2030 working plan identifies furniture and mattresses among priority product groups for consideration.
Business implication
Furniture development teams must begin asking:
- Can covers be replaced?
- Can hinges and slides be serviced?
- Can upholstery components be separated?
- Are spare parts available?
- Can the item be disassembled without destruction?
- Is the material composition documented?
- How will repair information reach the customer?
Sustainability is moving from claims into product architecture.
Digital Product Passports Are Moving Closer
The European Commission’s Digital Product Passport Registry became operational on 20 July 2026. Further standards and sector-specific requirements are advancing through the implementation timetable. European Commission
A DPP is intended to act as a digital container for product, component and material information.
Future furniture information could include:
- Product identifier
- Manufacturer
- Material composition
- Sustainability characteristics
- Repair information
- Spare parts
- Disassembly instructions
- Compliance evidence
- End-of-life guidance
Specific furniture obligations will depend on future legislation, so businesses should avoid presenting proposed requirements as already final.
Nevertheless, manufacturers can prepare immediately by improving:
- Model numbering
- Variant control
- Bills of materials
- Supplier records
- Test-report connections
- Repair instructions
- Digital documentation
The companies that begin early will face lower implementation risk later.
Circular Furniture Moves From Concept to Business Model
Europe is becoming a major testing ground for circular furniture.
Circular business models include:
- Repair
- Reupholstery
- Refurbishment
- Resale
- Rental
- Leasing
- Buy-back
- Remanufacturing
- Component harvesting
- Material recycling
Office furniture is well suited to circularity
Businesses frequently replace furniture during relocation or refurbishment even when much of it remains usable.
A circular provider can:
- Audit assets
- Repair products
- Reconfigure workstations
- Refinish surfaces
- Replace upholstery
- Resell surplus items
- Recycle unusable components
Residential opportunity
Consumers need simple access to:
- Replacement covers
- Hinges
- Drawer runners
- Legs
- Handles
- Cushion fillings
- Assembly hardware
A product cannot be considered practically repairable if the customer cannot find the required part or service provider.
Sustainability Claims Will Face Greater Scrutiny
Terms such as “green,” “eco-friendly,” “responsible” and “sustainable” are increasingly inadequate without evidence.
Furniture companies should substantiate claims concerning:
- Certified timber
- Recycled content
- Carbon footprint
- Local production
- Non-toxic materials
- Durability
- Repairability
- Recyclability
Common risks
- Claiming a whole product is certified when only one material is covered
- Using outdated certificates
- Failing to connect evidence with the marketed model
- Treating recyclable material as proof that the entire product is recyclable
- Ignoring adhesives, coatings and mixed materials
- Making carbon claims without explaining methodology
Transparency should include limitations—not only benefits.
Europe’s Contract Furniture Opportunity
Residential demand is weak, but contract markets can provide growth.
Promising categories include:
- Hotels
- Restaurants
- Offices
- Healthcare
- Senior living
- Education
- Student accommodation
- Public buildings
- Retail interiors
- Transport facilities
European suppliers have advantages in:
- Design
- Fire and safety compliance
- Project management
- Customisation
- Installation
- Replacement support
- Technical documentation
However, contract work carries risks:
- Long payment cycles
- Project delays
- Material approvals
- Site-access problems
- Installation liability
- Specification changes
Manufacturers entering contract markets need financial and project-management capability, not only suitable products.
How European Manufacturers Can Compete
European companies cannot win every product category through price.
A stronger competitive model combines:
Design
Products should solve genuine spatial, demographic and workplace problems.
Speed
Regional production can reduce lead times and inventory exposure.
Customisation
Factories can offer finishes, dimensions and configurations tailored to projects.
Documentation
Accurate product records can simplify procurement and regulatory compliance.
Repairability
Spare parts and service can extend product life.
Provenance
Local materials, craftsmanship and manufacturing identity can strengthen value.
Trust
Independent reviews, case studies and verified claims reduce buyer uncertainty.
The European advantage is not simply “Made in Europe.” It is the combination of design, engineering, proximity, documentation and service.
Strategic Action Plan
For manufacturers
- Audit exposure to energy-price increases.
- Map imported materials and components.
- Prepare EUDR documentation.
- Standardise model and variant records.
- Develop repair and spare-parts programmes.
- Examine automation and material efficiency.
- Reduce customer concentration.
- Strengthen contract-market capabilities.
For importers
- Identify potentially covered EUDR products.
- Require supplier traceability before shipment.
- Recalculate landed costs.
- Review tariff classifications.
- Assess alternative sourcing countries.
- Verify environmental claims.
For retailers
- Replace permanent discounting with clear value.
- Improve digital product information.
- Offer measurement, delivery and assembly services.
- Collect verified customer reviews.
- Introduce repair, take-back or resale options.
- Monitor supplier financial health.
For designers
- Specify durable components.
- Design for disassembly.
- Avoid unnecessary material mixing.
- Include replacement parts.
- Document material choices.
- Consider smaller homes and ageing users.
For associations and policymakers
- Help SMEs understand new regulations.
- Improve manufacturing and retail statistics.
- Support testing and certification.
- Develop repair skills.
- Encourage interoperable product data.
- Promote European suppliers internationally.
Europe’s Visibility and Connectivity Gap
Europe has globally respected furniture companies, but thousands of manufacturers, artisans, component suppliers, designers, installers and repairers remain difficult to discover.
Many SMEs depend on:
- Trade fairs
- Local distributors
- Architect relationships
- Traditional sales agents
- Word of mouth
These channels remain valuable, but they do not create continuous global visibility.
A manufacturer may be technically excellent yet invisible to:
- Overseas buyers
- Hotel developers
- Designers
- AI search systems
- International media
- Procurement platforms
Europe’s furniture transition therefore requires more than regulation and manufacturing investment. It requires better digital identity and industry connectivity.
TFT, FISE and FurniReviewology: Building the Missing Information Layer
The European furniture industry needs connected infrastructure supporting visibility, discovery and trust.
The Furniture Times
TFT can report:
- Company investments
- Factory transformations
- Regulatory developments
- Export achievements
- Circular initiatives
- Retail changes
- Design innovation
Furniture Industry Search Engine
FISE can make European participants searchable by:
- Country
- Product category
- Material
- Manufacturing capability
- Certification
- Market segment
- Service
FurniReviewology
FurniReviewology can organise credible information about:
- Product quality
- Supplier reliability
- Retail experience
- Delivery
- Installation
- Warranty
- Repair
Together:
The Furniture Times tells their story.
Furniture Industry Search Engine helps the world find them.
FurniReviewology helps the world trust them.
Editorial Conclusion
Europe’s furniture industry is not simply declining or recovering.
It is being restructured.
Weak residential demand is exposing undifferentiated products and inefficient retail models. High energy costs are forcing factories to improve productivity. Imports are increasing pressure on mass-market manufacturers. Exporters must navigate tariffs and geopolitical risk. Regulation is turning sustainability from a promotional claim into a documented product requirement.
The greatest opportunities lie in:
- Premium design
- Contract furniture
- Regional production
- Smaller-space products
- Senior-living furniture
- Repair and refurbishment
- Digital product information
- Circular services
- Verified sustainability
Europe’s future furniture advantage will not come from producing the cheapest item.
It will come from producing furniture that is better designed, better documented, easier to repair, more transparently sourced and supported throughout its life.
The industry must protect craftsmanship while embracing data.
It must preserve design leadership while improving affordability.
It must comply with regulation while turning compliance into competitive value.
The transformation will be difficult—but Europe possesses the design culture, engineering knowledge and manufacturing experience to lead it.
The Global Furniture Ecosystem
The Furniture Industry is a $1 Trillion USD Ecosystem in the world.
Furniture Industry Search Engine – FISE helps the world find them.
The Furniture Times – TFT tells their story.
FurniReviewology helps the world trust them.
If you are not searchable, you do not exist.
Be the next one. Be part of the movement.
Sources:
Eurostat—Industrial Production Statistics, European Commission—Digital Product Passport, European Commission—EUDR Implementation, European Commission—Furniture Industry, Intesa Sanpaolo—Furniture and Made in Italy Design