Monthly Global Furniture Industry Report
Monthly Global Furniture Industry Report: Markets, Materials, Manufacturing and Retail
October 2026 intelligence review of demand, housing, timber, panels, metals, upholstery, factory investment, global sourcing, freight, regulation, retail performance and the outlook for 2027
By The Furniture Times (TFT) Editorial Desk | Global Furniture Industry News | Monthly Market Intelligence | Materials | Manufacturing | Trade | Logistics | Retail | Policy | Investment
The global furniture industry reached the final quarter of 2026 with international trade showing greater resilience than previously expected—but furniture demand remaining sharply divided by country, customer group and product category.
Residential furniture continues to face pressure in markets where expensive mortgages, weak property transactions and high living costs are delaying household purchases. Contract furniture is benefiting from hotel development, office reconfiguration, healthcare, education and institutional investment. Manufacturers are cautiously expanding capacity in selected emerging markets, while many established factories are concentrating on automation, product flexibility and inventory control rather than volume alone.
At the same time, furniture companies face an increasingly complex operating environment.
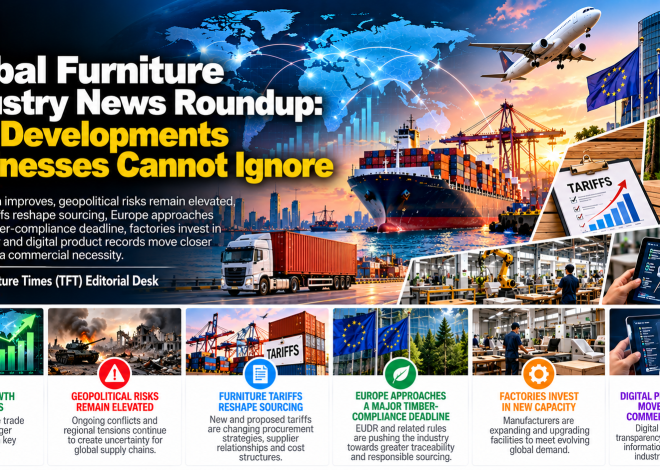
Middle East conflict has elevated energy, marine insurance and freight risks. US furniture tariffs are changing the economics of imported upholstery, kitchen cabinets and vanities. The European Union Deforestation Regulation is approaching a critical application date. Digital Product Passports are moving closer to the furniture sector. Buyers are demanding stronger product documentation, while consumers remain extremely sensitive to price, delivery and trust.
This inaugural Monthly Global Furniture Industry Report establishes a recurring intelligence framework for The Furniture Times. It monitors the complete value chain:
- Raw materials
- Components and accessories
- Furniture manufacturing
- Machinery and technology
- Global sourcing
- Trade and logistics
- Residential and contract markets
- Wholesale and retail
- Regulation and sustainability
- Investment and business confidence
The objective is not simply to report isolated announcements. It is to explain how developments across the entire ecosystem affect business decisions.
October 2026 Global Furniture Industry Dashboard
| Indicator | Current direction | TFT assessment |
|---|---|---|
| Global merchandise trade | Improving | Positive, but gains are uneven |
| Global economic growth | Moderate | Stable but vulnerable |
| Residential furniture demand | Mixed to weak | Housing affordability remains the principal constraint |
| Contract furniture demand | Selectively improving | Hospitality, office and institutional projects offer opportunities |
| Timber and wood products | Mixed | Compliance and origin documentation are increasingly important |
| Engineered wood panels | Stable to growing in selected markets | Modular and space-efficient furniture support demand |
| Metal inputs | Volatile | Energy, trade measures and carbon regulation remain risks |
| Foam and upholstery inputs | Cost-sensitive | Energy and petrochemical exposure requires monitoring |
| Container freight | High and volatile | Major risk for bulky, low-value furniture |
| Factory investment | Selective | India and Southeast Asia remain important growth centres |
| Furniture retail | Uneven | Premium and value segments outperform undifferentiated middle-market offers |
| Inventory conditions | Improving selectively | Retailers remain cautious about over-ordering |
| Regulatory pressure | Rising | EUDR, product data and sustainability requirements demand action |
| Industry confidence | Cautiously neutral | Opportunity exists, but visibility remains limited |
1. Global economic environment: resilient but not comfortable
The global economy has avoided the worst outcomes feared earlier in 2026, but businesses should not confuse resilience with strength.
The International Monetary Fund’s October 2026 assessment projected global economic growth of approximately 3.1% in 2026 and 3.4% in 2027. The IMF said the global economy remained resilient, while warning that resilience was under strain and risks remained tilted to the downside. Higher energy and food prices are contributing to near-term inflationary pressure.
Furniture is particularly sensitive to this environment because it depends heavily on discretionary expenditure, construction, property transactions and access to credit.
Consumers may continue spending on essential replacement items, mattresses, lower-priced storage and practical home-office furniture while postponing larger purchases such as complete bedroom, living-room and dining-room packages.
Businesses may continue buying ergonomic seating, collaborative furniture or hospitality furnishings, but purchasing committees are increasingly demanding evidence of lifecycle value.
The central economic contradiction
The industry is operating between two realities:
- Global activity is still expanding.
- Many consumers do not feel financially secure enough to make large discretionary purchases.
This explains why furniture markets can appear healthy at the macro level while individual retailers experience weak store traffic and aggressive promotional pressure.
2. Global trade: stronger figures, uneven furniture benefits
The World Trade Organization’s October update forecasts world merchandise-trade volume growth of 3.9% in 2026 and 4.1% in 2027, substantially stronger than its earlier 2026 projection. The WTO attributed part of this resilience to better first-half trade and continued AI-related investment.
This is a positive background indicator for furniture exporters, but it does not mean furniture trade will grow at the same pace.
Technology equipment and AI-related infrastructure are contributing heavily to the improvement. Furniture still faces category-specific barriers, including:
- High freight-to-product-value ratios
- Housing-market weakness
- Furniture-specific tariffs
- Long replenishment cycles
- Retail inventory caution
- Timber-traceability requirements
- Product-safety and testing costs
- Currency volatility
Where the stronger trade environment may help
Export opportunities are more likely in:
- Hospitality furniture
- Office and collaborative furniture
- Healthcare furniture
- Educational and institutional furniture
- Outdoor and leisure products
- Modular and compact furniture
- Ready-to-assemble products
- Furniture components and hardware
- Woodworking machinery
- Specialised logistics and installation services
The 2026 market is rewarding flexibility rather than pure scale. A factory capable of handling smaller batches, customised specifications and rapid documentation may be more competitive than a larger plant dependent on one country or one retailer.
3. Residential market: housing activity remains decisive
Residential furniture demand remains closely connected to housing turnover.
People typically spend on furniture when they:
- Purchase a home
- Move between properties
- Renovate
- Form a new household
- Welcome a child
- Start working from home
- Replace damaged or outdated items
When property transactions slow, furniture demand can weaken even if house prices remain high.
United States
US existing-home sales increased by 1.5% in September to an annualised rate of 3.99 million units. However, activity remained subdued, sales were down year over year, mortgage rates were around 7.4%, and the median price reached a September record of US$417,500. Inventory improved, but affordability continued to constrain demand.
Furniture implications
The US market may see:
- Continued demand for value and promotional furniture
- Stronger premium activity among wealthier buyers
- Weakness in broad middle-income replacement demand
- Longer consumer decision cycles
- Increased use of financing
- Reduced tolerance for delivery charges
- More competition for every transaction
The increase in available homes is not enough by itself. Furniture demand requires completed transactions and financially confident buyers.
Australia
Australia offers a clear example of how declining housing turnover affects the broader home economy.
Housing transactions reportedly fell approximately 15% year over year during the recent downturn. Reuters estimated that reduced turnover was removing between A$355 million and A$710 million per month from property-related spending, affecting furniture retailers, home stylists, movers, landscapers and tradespeople.
Furniture retailer Nick Scali experienced weaker store traffic amid housing and consumer pressure, while Harvey Norman also reported pressure on parts of its furniture-linked operations.
The Australian experience demonstrates that furniture businesses should monitor transaction volumes—not merely property prices.
Europe
European furniture demand remains divided.
Consumers continue prioritising value, energy bills and essential expenditure. Import penetration has increased over the longer term, placing additional pressure on European manufacturers competing with lower-cost overseas production. Available industry reporting indicates that imported furniture has grown faster than European-produced furniture supplied to the regional market in recent years.
European manufacturers retain strengths in:
- Premium design
- Brand heritage
- Contract furniture
- Advanced machinery
- Sustainable materials
- Product engineering
- Shorter regional lead times
However, they must manage energy costs, labour expenses, regulatory compliance and import competition.
4. Contract markets: an increasingly important demand engine
The contract furniture sector continues to offer an alternative growth path when residential demand is weak.
The category includes furniture for:
- Hotels and resorts
- Restaurants and cafés
- Corporate offices
- Healthcare facilities
- Schools and universities
- Student accommodation
- Senior living
- Government buildings
- Retail stores
- Airports and transport hubs
- Co-living properties
- Serviced residences
Why the segment matters
Contract purchases are driven less directly by consumer confidence. They respond to construction pipelines, tourism, business investment, public budgets and property refurbishment.
A hotel opening may require furniture for hundreds of rooms as well as:
- Reception areas
- Restaurants
- Lounges
- Pool decks
- Meeting rooms
- Staff facilities
- Outdoor spaces
An office refurbishment may require task chairs, height-adjustable desks, acoustic pods, collaborative tables and flexible storage.
The operational difference
Contract furniture is not simply residential furniture ordered in larger quantities.
It may require:
- Fire-performance evidence
- Commercial durability testing
- Approved samples
- Mock-up rooms
- Precise drawings
- Material schedules
- Finish control
- Delivery sequencing
- On-site installation
- Snagging and rectification
- Replacement availability
Manufacturers seeking contract business must build a project-management system around the product.
5. Timber and solid wood: traceability becomes as important as price
Timber remains one of the furniture industry’s most strategically important materials, but purchasing decisions can no longer be based only on species, grade, moisture content and cost.
Manufacturers and buyers increasingly need to understand:
- Country of harvest
- Legal status
- Deforestation risk
- Species identification
- Chain of custody
- Batch connection
- Supplier credibility
- Certification status
- Documentation retention
The EU Deforestation Regulation is scheduled to apply from 30 December 2026 to large and medium operators, with later application for many micro and small enterprises. Covered businesses must demonstrate that relevant commodities and derived products meet the regulation’s deforestation-free and due-diligence requirements.
October priority
Furniture companies supplying the European market should now be testing whether they can connect a finished product with its timber evidence.
For example, a wooden cabinet may include:
- Solid-rubberwood frame
- MDF doors
- Plywood drawer base
- Veneer surface
- Wooden handles
- Timber packaging supports
The company must understand which components are relevant, where they originated and how the records connect to a particular model or shipment.
Commercial risk
A supplier may be using legitimate timber but still become commercially unusable if it cannot provide the necessary information.
Traceability is therefore becoming a supplier-selection criterion.
6. Engineered wood: modular furniture supports continued relevance
MDF, particleboard, plywood, oriented-strand products and laminated panels remain essential to mass-market and modular furniture.
Demand is supported by:
- Smaller urban homes
- Modular kitchens
- Wardrobe systems
- Ready-to-assemble furniture
- Built-in storage
- Office furniture
- Retail fixtures
- Lower-cost residential products
India demonstrates this structural trend. Industry analysis has highlighted growing demand for MDF and particleboard as compact homes and modular interiors expand, while established plywood manufacturers invest in engineered-panel categories.
Issues manufacturers must monitor
- Resin and chemical costs
- Formaldehyde and emission limits
- Moisture resistance
- Surface quality
- Panel density
- Edge integrity
- Screw-holding performance
- Lamination quality
- Recycled content
- Responsible fibre sourcing
A board’s purchase price does not reveal its true production cost. Poor consistency can create machining defects, delamination, returned products and premature furniture failure.
7. Metals: a crucial but underreported furniture input
Steel, aluminium and stainless steel are fundamental across the furniture ecosystem.
They are used in:
- Office-chair bases
- Recliner mechanisms
- Sofa frames
- Table legs
- Storage systems
- Hospital furniture
- Outdoor furniture
- Shelving
- Fasteners
- Hinges
- Drawer slides
- Bed frames
- Institutional seating
Metal furniture and components remain exposed to energy prices, trade restrictions, carbon regulation, currency movements and industrial demand.
Furniture companies should watch
- Coil and tube prices
- Aluminium extrusion costs
- Stainless-steel surcharges
- Powder-coating costs
- Welding labour
- Corrosion protection
- Freight costs
- Lead times for specialised mechanisms
The European Carbon Border Adjustment Mechanism does not treat finished furniture as though every product automatically falls within its initial material categories. Nevertheless, furniture manufacturers importing covered steel or aluminium inputs—or buying from suppliers affected by carbon costs—may experience indirect pricing and documentation effects.
Material compliance must be assessed by product and customs classification, not by assumption.
8. Foam, textiles and upholstery: energy and petrochemicals remain key risks
Upholstered furniture depends on a complex supply chain involving:
- Polyurethane foam
- Polyester fibre
- Fabrics
- Leather
- Synthetic leather
- Webbing
- Springs
- Adhesives
- Thread
- Zippers
- Mechanisms
Foam and synthetic textile production are connected to petrochemical inputs. Middle East instability can therefore affect upholstery through energy prices, chemical feedstocks, shipping and insurance—even when the finished furniture is manufactured elsewhere.
Quality risk during cost pressure
When input costs rise, some suppliers may attempt to protect margins by reducing:
- Foam density
- Fabric weight
- Leather grade
- Coating thickness
- Spring quality
- Filling quantity
- Stitch density
These changes may not be immediately visible, but they can shorten furniture life significantly.
Manufacturers should maintain approved specifications and test incoming materials rather than accepting an apparently equivalent substitution.
9. Components and accessories: small parts carry large commercial risks
Furniture components are often treated as low-cost purchasing items, but they determine how the product functions.
The category includes:
- Hinges
- Drawer slides
- Castors
- Connectors
- Fasteners
- Gas lifts
- Recliner mechanisms
- Handles
- Levelling feet
- Locks
- Electrical modules
- Motion systems
A small component failure can make an entire wardrobe, chair, desk or recliner unusable.
October purchasing priorities
Companies should review:
- Component failure rates
- Supplier consistency
- Spare-part availability
- Load testing
- Cycle testing
- Corrosion resistance
- Compatibility across models
- Batch identification
- Warranty recovery
Component standardisation can simplify inventory, repairs and after-sales service, but excessive dependence on one source creates continuity risk.
10. Manufacturing: investment continues, but the model is changing
Factories are not simply adding production lines. They are reconsidering what manufacturing capacity should accomplish.
The current priority areas include:
- CNC machining
- Automated cutting
- Robotic finishing
- Digital nesting
- Material optimisation
- Defect detection
- Mass customisation
- Shorter changeover times
- Energy efficiency
- Production traceability
- Real-time quality monitoring
Industry analysis indicates that manufacturers are reducing overproduction risk, diversifying supply chains and increasing automation and artificial-intelligence applications.
India: new capacity near Hyderabad
Fabience recently announced plans for a greenfield premium furniture manufacturing facility near Hyderabad, intended to expand production and support international exports.
The investment reinforces India’s growing importance as both a consumption market and an export-manufacturing location.
India’s long-term opportunity includes:
- Large domestic demand
- Hospitality development
- Office expansion
- Skilled craft traditions
- Growing panel production
- Engineering capacity
- Export diversification
Success will depend on documentation, product consistency, packaging and delivery—not merely manufacturing cost.
Vietnam: continued sourcing importance
Vietnam remains an important furniture-export centre as buyers diversify production beyond China. The outlook remains broadly favourable, although geopolitical tensions, residential-market fluctuations, currency pressure and compliance requirements create near-term challenges.
Malaysia: manufacturing foundation remains strategically valuable
Malaysia’s overall manufacturing sales increased by 9.9% year over year in August 2026, although the strongest growth came from electrical and electronics rather than furniture. The wider industrial performance indicates the importance of Malaysia’s manufacturing infrastructure, logistics and supplier ecosystem.
For Malaysian furniture manufacturers, the priority is to move beyond commodity competition through:
- Original design
- Branded manufacturing
- Automation
- Material transparency
- Contract capability
- Fast sampling
- Better digital visibility
11. Global sourcing: diversification becomes permanent
For years, companies discussed “China plus one.” The present environment is producing a more complex sourcing model.
Large buyers increasingly require:
- Multiple production countries
- Alternative material suppliers
- Regional assembly options
- Backup freight routes
- Product-level compliance records
- Faster replacement availability
- Flexible minimum-order quantities
Major sourcing roles
| Market | Strategic strengths |
|---|---|
| China | Scale, machinery, integrated components, rapid product development |
| Vietnam | Export furniture, wood manufacturing, established buyer relationships |
| Malaysia | Furniture clusters, rubberwood, international sourcing access |
| Indonesia | Solid wood, rattan, craft capability and natural materials |
| India | Domestic scale, design, craft and emerging industrial capacity |
| Turkey | Access to Europe, Middle East and regional markets |
| Eastern Europe | EU proximity, woodworking skills and shorter lead times |
| Mexico | North American proximity and nearshoring potential |
Diversification should not mean adding suppliers without management capacity. More countries create more documentation, quality-control and logistics requirements.
The objective is controlled resilience, not uncontrolled complexity.
12. Freight and logistics: one of the month’s greatest risks
Container freight remains an important threat to furniture margins.
Rates from China to the US East Coast moved toward pandemic-era levels during September as Middle East conflict increased fuel costs. One industry benchmark placed the route near US$10,948 per 40-foot container, while Drewry recorded Shanghai-to-New York pricing above US$10,000 during the period.
European carriers and logistics groups were expected to report strong third-quarter results because elevated rates and resilient trade benefited parts of the shipping industry. For furniture importers, however, carrier strength can mean higher landed costs.
Why furniture is highly exposed
A container can carry thousands of small electronic products but only a limited number of assembled sofas, wardrobes or dining sets.
Furniture companies must therefore improve:
- Flat-pack engineering
- Carton dimensions
- Product nesting
- Component consolidation
- Load planning
- Damage prevention
- Warehouse coordination
- Route comparison
- Shipment visibility
The dangerous purchasing mistake
A low factory price can become expensive after adding:
- Ocean freight
- Port charges
- Insurance
- Customs duty
- Tariffs
- Demurrage
- Warehousing
- Last-mile delivery
- Damage
- Installation
- Returns
Furniture should be purchased on total landed and lifecycle cost, not ex-factory price alone.
13. Retail: the value proposition is under examination
Furniture retailers face one of the most demanding consumer environments in recent years.
Consumers are comparing:
- Price
- Delivery time
- Reviews
- Warranty
- Materials
- Dimensions
- Assembly
- Return policies
- Financing
- Retailer reputation
A discount is no longer sufficient if the customer is uncertain about quality or delivery.
Three retail segments are emerging
1. Price-led retail
This segment competes through affordability, availability and convenience.
Winning requires cost discipline, dependable stock and clear product information.
2. Premium and design-led retail
This segment competes through design, provenance, materials, craftsmanship, service and exclusivity.
Winning requires storytelling supported by evidence.
3. Service-led retail
This segment competes through consultation, customisation, measurement, delivery, installation, repair and after-sales support.
Winning requires operational reliability.
The most vulnerable retailers are those offering generic furniture at mid-market prices without distinctive design, better service or stronger trust.
14. E-commerce: furniture discovery is digital even when purchasing is physical
Furniture remains a category in which many customers want to touch, sit on or inspect the product. Nevertheless, the buying journey commonly begins online.
Consumers use digital channels to:
- Discover brands
- Compare dimensions
- Check prices
- Read reviews
- View customer photos
- Examine materials
- Confirm store locations
- Explore delivery terms
- Create shortlists
This means physical retailers need complete digital product information.
Minimum digital requirements
Every important furniture product should have:
- Accurate name and model number
- Dimensions
- Material description
- Finish or colour
- Assembly status
- Weight or capacity where relevant
- Delivery information
- Care instructions
- Warranty
- Multiple images
- Availability
- Verified reviews
A product displayed online without sufficient information is not merely under-marketed. It may be removed from the buyer’s shortlist before the retailer receives an enquiry.
15. Regulation: compliance becomes part of market access
Furniture companies increasingly face a connected set of obligations involving:
- Timber legality and deforestation
- Product safety
- Chemical emissions
- Flammability
- Labelling
- Packaging waste
- Producer responsibility
- Repairability
- Sustainability claims
- Product data
- Customs origin
The European Commission launched its central Digital Product Passport resource and registry in July 2026. Furniture is among the product groups identified for future DPP implementation under the Ecodesign for Sustainable Products Regulation.
Business implication
Compliance departments can no longer operate only when a shipment or certification application is due.
Product information must be built correctly from the beginning:
Model → Variant → Drawing → Bill of Materials → Supplier Records
      → Test Reports → Production Batch → Shipment → Customer
If these records do not agree, certification, customs clearance, warranty investigation and product-passport implementation become more difficult.
16. Technology: AI grows, but verified data remains the foundation
Artificial intelligence is entering furniture design, manufacturing, marketing and retail.
Applications include:
- Room visualisation
- Product recommendations
- Automated quotations
- Demand forecasting
- Production scheduling
- Defect detection
- Inventory planning
- Image generation
- Catalogue translation
- Customer service
However, AI cannot correct unreliable source data.
If dimensions, prices, stock status or material descriptions are wrong, automation can distribute those errors faster.
The correct sequence
- Establish accurate product records.
- Standardise models and variants.
- Connect digital assets.
- Define approval responsibility.
- Add automation and AI.
- Monitor output quality.
The furniture industry needs verified intelligence—not merely faster content production.
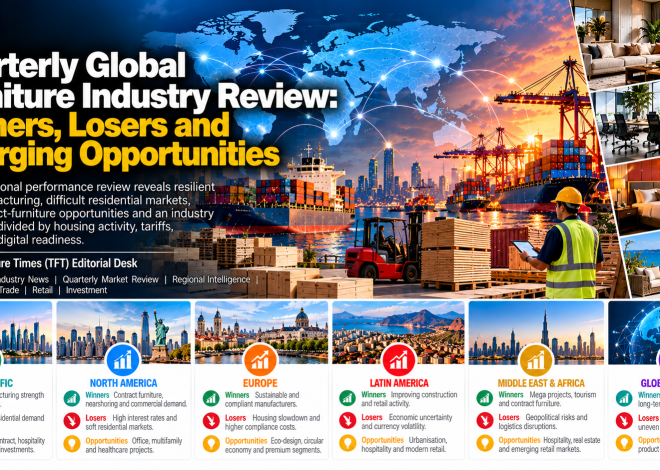
Regional Performance Review
Asia-Pacific
Assessment: Most important long-term growth and production region.
Opportunities are supported by urbanisation, middle-class growth, hospitality development, manufacturing investment and smaller-space living.
Risks include export tariffs, uneven property markets, currency volatility and dependence on global shipping.
North America
Assessment: Large but highly policy- and housing-sensitive.
Demand is constrained by mortgage costs and affordability, while furniture tariffs favour some regional producers and challenge importers.
Premium consumers remain active, but the broad middle market is cautious.
Europe
Assessment: Mature, design-led and compliance-intensive.
Demand remains mixed. Manufacturers face cost and import pressure but retain leadership in machinery, premium design, sustainability and contract furniture.
EUDR and future product-passport requirements require immediate preparation.
Middle East
Assessment: Strong project potential under exceptional geopolitical risk.
Hospitality, luxury residential, commercial development and public investment support furniture opportunities. Conflict, energy volatility, insurance costs and shipping disruption create major uncertainty.
India
Assessment: One of the strongest structural opportunities.
Domestic consumption, modular interiors, hotel development, offices and export-oriented manufacturing support growth. Quality standardisation and formalisation remain decisive.
Africa
Assessment: Long-term opportunity with uneven near-term conditions.
Urbanisation, housing demand, hospitality and local manufacturing create potential. Financing costs, infrastructure, imported-material dependence and currency pressure constrain expansion.
Latin America
Assessment: Selective opportunity led by regional production and domestic demand.
Brazil, Mexico and other manufacturing centres can benefit from regional trade and nearshoring, but economic and currency conditions remain uneven.
TFT Outlook for the Remainder of 2026
The Furniture Times expects the final months of 2026 to be defined by seven major themes:
- Selective demand rather than broad recovery
Strong projects and markets will coexist with weak residential categories. - Continued freight volatility
Conflict and route disruption will keep quotations vulnerable. - Accelerating EUDR preparation
European buyers will pressure suppliers for better timber records. - Tariff-driven sourcing reviews
Importers will reassess countries, classifications and assembly locations. - Cautious factory investment
Capital will favour automation, flexibility and traceability. - Retail margin pressure
Discounting and high logistics costs will challenge profitability. - Greater demand for verified industry intelligence
Companies will need better visibility into suppliers, customers, regulations and market developments.
Management Action Checklist for October
Manufacturers
- Review exposure to tariffs and freight surcharges.
- Map timber and wood-component origins.
- Standardise model and variant documentation.
- Calculate profitability by product and export market.
- Reduce unnecessary packaging volume.
- Review critical component suppliers.
- Build contract-market documentation.
- Prepare digital product records.
Suppliers
- Provide current technical data.
- Connect materials to batch and origin records.
- Notify customers before substitutions.
- Maintain independent test evidence.
- Improve spare-parts continuity.
Retailers
- Compare inventory with actual sales velocity.
- Identify products damaged by excessive discounting.
- Improve online specifications and photography.
- Strengthen reviews and after-sales service.
- Prepare alternative suppliers for critical categories.
- Measure delivery failures and returns.
Logistics providers
- Update war-risk and fuel surcharges.
- Offer alternative routes.
- Improve furniture-specific damage controls.
- Provide shipment visibility.
- Strengthen customs and regulatory support.
- Develop reverse-logistics capability.
Designers
- Design for transport efficiency.
- Reduce unnecessary material complexity.
- specify replaceable components.
- Document every approved variant.
- Consider repair, disassembly and recycling.
Building a Global Furniture Intelligence Infrastructure
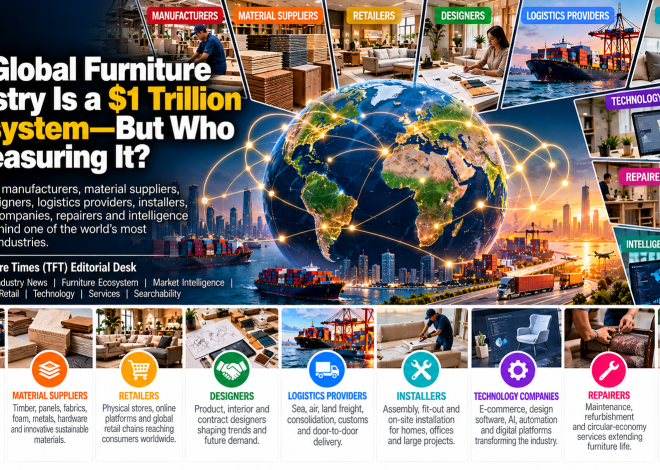
The global furniture industry cannot be understood through product-sales estimates alone.
It includes:
- Forests and timber processors
- Panel producers
- Metal and chemical industries
- Textile, foam and leather suppliers
- Component manufacturers
- Furniture factories
- Designers and architects
- Testing laboratories
- Certification specialists
- Importers and exporters
- Logistics providers
- Wholesalers and retailers
- Installers and repairers
- Technology companies
- Media and market-intelligence platforms
The furniture industry ecosystem is a $1 trillion industry ecosystem, but it remains fragmented and inadequately measured.
This monthly report is designed to help close that intelligence gap.
The future requires three connected layers:
The Furniture Times tells their story.
Furniture Industry Search Engine helps the world find them.
FurniReviewology helps the world trust them.
TFT converts developments into industry intelligence.
FISE connects businesses across countries, sectors and product categories.
FurniReviewology creates a structured trust and reputation layer.
Together, they can help make the furniture ecosystem more visible, searchable, credible and commercially connected.
Editorial Conclusion
October 2026 presents neither a furniture boom nor a universal downturn.
It presents a restructuring.
Global trade is stronger than previously expected, but residential demand remains restricted by housing affordability. Factories are investing, but buyers require greater flexibility and traceability. Contract furniture offers growth, but suppliers must meet demanding technical requirements. Digital commerce expands discovery, but incomplete product information destroys confidence. Environmental regulation creates compliance pressure, but it also rewards organised and transparent businesses.
The companies best positioned for 2027 will not necessarily be the largest.
They will be the businesses that can answer six questions clearly:
- What exactly do you manufacture, supply or sell?
- Can you prove the origin and specification of your materials?
- Can you deliver reliably despite disruption?
- Can buyers find and understand your company?
- Do independent customers and partners trust you?
- Can you adapt when markets, costs or regulations change?
The furniture industry no longer needs isolated statistics and promotional claims. It needs continuous, connected and actionable intelligence.
If you are not searchable, you do not exist.
Be the next one. Be part of the movement.
Proposed Monthly TFT Reporting Framework
Every future edition can follow these recurring sections:
- Executive Industry Dashboard
- Global Economy and Trade
- Residential Demand
- Contract and Project Markets
- Materials Monitor
- Components and Accessories
- Manufacturing and Factory Investment
- Technology and Machinery
- Global Sourcing
- Freight and Logistics
- Wholesale and Retail
- Regulation and Sustainability
- Regional Performance
- Company Announcements
- Monthly Risks and Opportunities
- Management Action Checklist
- 90-Day Outlook
This format allows businesses to compare developments consistently from month to month.
Sources:
World Trade Organization—Global Trade Outlook and Statistics, International Monetary Fund—World Economic Outlook, UN Trade and Development—Transport and Trade Logistics, European Commission—Deforestation Regulation, European Commission—Digital Product Passport, Department of Statistics Malaysia—Manufacturing Statistics